Newsroom
Blog & resources
Plain-English guidance and real Utah data on long-term care, Social Security, and retirement income — written for the people we serve, not for search engines.
High-Deductible Plan G in Utah: 2027 Deductible Is $3,050
CMS set the 2027 deductible for high-deductible Medigap Plans F, G and J at $3,050, up from $2,950 in 2026 after a 3.40% CPI-U increase and 30.3% higher than in 2020. You pay Medicare-covered coinsurance, copays and deductibles up to $3,050, then the policy pays like standard Plan G; premiums and Part D drug costs don't count. In Utah, 11,142 people had high-deductible G in 2024, up from 1 in 2020, and about 33.2% of the state's 79,785 Medigap members had a high-deductible plan (Utah Insurance Department). Because standard G also leaves you the Part B deductible, the most extra you can owe is about $2,767 a year. Plus a break-even table, a comparison with 2027 Medicare Advantage out-of-pocket limits ($9,850 maximum), HSA rules and a checklist.
Read →
Year-End Tax Moves for Utah Retirees: 2026 Checklist
Most retiree tax moves have a December 31, 2026 deadline. Take your RMD on time: a missed one can owe a 25% excise tax, or 10% if corrected within two years (IRS). At 70½ or older, you can give up to $111,000 per person by qualified charitable distribution, which counts toward your RMD and stays out of AGI. A couple who are both 65+ can deduct up to $47,500 in 2026, so about $148,300 of income keeps them in the 12% bracket, and long-term gains are taxed at 0% up to $98,900 of joint taxable income (Rev. Proc. 2025-32). Utah's rate is a flat 4.5%, but in the Social Security credit phase-out range extra income costs about 7% in Utah tax (Utah Code 59-10-1042). 2026 income generally sets 2028 Medicare IRMAA. Only 13.3% of Utah returns itemized in tax year 2023 (IRS SOI). Plus a 7-step year-end checklist.
Read →
The $6,000 Senior Deduction: What Utah Retirees Get (2026)
For tax years 2025 through 2028, each person 65 or older can deduct an extra $6,000 on their federal return, or $12,000 for a couple when both qualify, with or without itemizing (IRS). It phases out by 6% of income above $75,000 (single) or $150,000 (joint) and is gone at $175,000 and $250,000. For 2026, a single filer 65+ can deduct up to $24,150 in total and a couple both 65+ up to $47,500. Utah's 4.5% tax barely changes, because Utah starts from federal AGI and its taxpayer credit uses line 12e, not the senior deduction on line 13b. It does not lower Medicare IRMAA or the tax on Social Security, and in the phase-out range it adds about 2.64 points to a couple's 22% Roth conversion rate. Plus four hypothetical Utah households, the 2026 stacking table and a year-end checklist; 434,922 Utahns were 65+ in 2024 (Census).
Read →
Utah Life Expectancy at 65: How Long to Plan For (2026)
A 65-year-old in Utah could expect about 19.0 more years in 2022, according to the CDC's newest state life tables: 18.2 for men and 19.8 for women. That is only an average. About 53% of 65-year-old Utah women and 46% of men reach 85, 28% of women reach 90, and for a 65-year-old couple there is about a 44% chance at least one reaches 90 and 14% that one reaches 95. Utah men at 65 outlive the national average by about 0.7 years, while Utah women sit 0.4 years below it. Life expectancy at birth ranges from 73.3 years in San Juan County to 84.7 in Summit County (Utah DHHS, 2019-2023). On a hypothetical $2,000 Social Security benefit, waiting from 62 to 70 pays more in total after about age 80, an age most 65-year-old Utahns reach. Plus survival odds to 100, county comparisons, survivor income and a five-step longevity checklist.
Read →
How Are Annuities Taxed in Utah? A 2026 Retiree Guide
Utah taxes whatever part of an annuity payment is taxable on your federal return at its flat 4.5% rate, with no separate exclusion for annuity or pension income. An annuity bought inside an IRA or 401(k) is generally fully taxable; one bought with after-tax money returns part of each payment tax-free under the IRS exclusion ratio until your cost is recovered. Withdrawals from a deferred annuity before payments start come out of earnings first, and under 59½ the taxable part can owe a 10% additional federal tax. In a hypothetical St. George example, $650 a month from a $100,000 after-tax annuity started at 70 is about 80% tax-free under IRS Table V, so Utah tax is about $70 a year instead of $351 from an IRA. In tax year 2023, 231,000 Utah returns reported $7.31 billion in taxable pensions and annuities (IRS). Plus the Simplified Method table, 1035 exchanges, the 3.8% investment income tax, how annuity income shrinks Utah's Social Security credit, IRMAA, heirs and a six-step checklist.
Read →
Utah URS Pension: Tier 1 vs Tier 2 Benefits Explained (2026)
Utah Code sets the URS Tier 1 noncontributory pension at 2% of your highest-three-year average salary per year of service, unreduced at 65 or with 30 years at any age, and the Tier 2 hybrid pension at 1.5% of your highest-five-year average per year of service since July 1, 2011, unreduced at 65 or with 35 years. Tier 1 trims early benefits 3% a year from 60 to 65; Tier 2 uses a full actuarial reduction. Cost-of-living raises are capped at 4% (Tier 1) and 2.5% (Tier 2) with excess inflation banked; URS's published figure topped the Tier 2 cap in five of the last ten years. On a $72,000 salary, 15 years pays about $1,800 a month under Tier 1 against $1,350 under Tier 2. Plus the Tier 2 401(k)-only path, FY2025-26 contribution rates, the six payment options, Utah tax and Medicare IRMAA, URS's 95% funded ratio and a six-step checklist before you file.
Read →
Where Should Utah Retirees Keep Cash? CDs vs T-Bills (2026)
The FDIC's national averages published October 19, 2026 were 0.38% for savings accounts, 0.63% for money market deposit accounts and 1.76% for a 12-month CD, while on October 16 a 52-week Treasury bill yielded 4.44% and a 13-week bill 4.18%. Consumer prices rose 3.7% in the year to September 2026, so the average savings account lost buying power. Utah exempts interest on Treasury bills, notes and savings bonds from its 4.5% income tax (TC-40A code 71) but taxes bank interest, so a CD would need about 4.65% to match a 4.44% T-bill after Utah tax. On $50,000 held for a year, a 52-week bill earns about $2,220 against $181 in the average savings account after Utah tax. Plus FDIC and NCUA limits, why money market funds and annuities are not FDIC-insured, Utah's 44 FDIC-insured institutions holding $1.05 trillion in deposits, I bonds at 4.26% through October 31, and a five-step cash ladder for Utah retirees.
Read →
What Does Retirement Cost in Utah? 2026 Retiree Budget
U.S. households headed by someone 65 or older spent an average of $61,432 in 2024, according to the Bureau of Labor Statistics: $65,354 at ages 65 to 74 and $55,834 at 75 and older, not counting income taxes. Utah's overall price level was 98.9 against a national 100 in 2024, so the 65+ average is about $60,734 at Utah prices, though Utah housing ran 7.8% above the nation and utilities about 21% below it; Salt Lake City and Ogden metro prices sat slightly above the national level and St. George and Logan below it. Health care is the one category that grows with age, at $7,799 a year for 65+ households and $7,918 after 75. On the income side, Utah householders 65 and older had a 2024 median income of $70,712 against $59,648 nationally, and 7.7% of Utahns 65+ lived in poverty against 11.2% nationally. An average couple's 2027 Social Security of about $40,260 leaves a gap of roughly $24,000 a year against a 65-to-74 budget at Utah prices. Plus a full spending table by age, Utah metro price levels, 65+ income for 11 Utah counties, the health care line and a six-step budget worksheet.
Read →
Does Medicare Cover Wegovy & Zepbound in Utah? (2026-27)
Yes, for now. Since July 1, 2026 the temporary Medicare GLP-1 Bridge has covered Wegovy (injection or tablet), Zepbound (KwikPen only) and Foundayo for weight management at $50 a month for eligible people with Part D, and CMS has extended it through December 31, 2027. You need a BMI of 35 or more, or 30 or more with certain heart, blood pressure or kidney conditions, or 27 or more with prediabetes or a past heart attack, stroke or artery disease; people with type 2 diabetes, moderate-to-severe sleep apnea or fatty liver disease go through their Part D plan instead. The $50 does not count toward the Part D deductible or the $2,400 cap in 2027. Separately, Medicare's negotiated price for Ozempic, Rybelsus and Wegovy is $274 for a 30-day supply from January 1, 2027, against a $959 list price. In 2024, 9,839 Utah Part D enrollees filled Ozempic (2.68% against 3.59% nationally) and 7,546 filled Mounjaro (2.06% against 1.64%). Plus who qualifies, how to apply through your doctor and pharmacy, adult obesity in all 29 Utah counties, Medicare's other weight-management benefits, and a St. George couple's 2027 drug budget on two different GLP-1 routes.
Read →
Medicare Open Enrollment Opens Today in Utah (2027 Plans)
Medicare Open Enrollment opened October 15, 2026 and runs through December 7, with new coverage starting January 1, 2027. CMS lists 51 Medicare Advantage plans in Utah for 2027, down from 55, and 8 stand-alone Part D plans, down from 10; the average Utah Medicare Advantage premium dipped from $9.59 to $9.16 a month and 99.79% of the state's 490,235 people with Medicare can get a $0-premium plan, which is not free since the Part B premium and cost-sharing still apply. The Part D out-of-pocket cap rises from $2,100 to $2,400 and the highest allowed deductible from $615 to $700, and the median out-of-pocket limit on Utah plans open to anyone went from $5,800 to $6,700. What you can change, why Open Enrollment doesn't guarantee a Medigap policy, the January 1 to March 31 second chance for Medicare Advantage members, and a this-week checklist: your Annual Notice of Change, doctors, prescriptions, IRMAA letter and your 2027 income budget.
Read →
2027 Social Security COLA: 3.6% Raise for Utah Retirees
Social Security benefits rise 3.6% for 2027, the Social Security Administration announced on October 14, 2026, up from 2.8% for 2026. The average retired worker goes from about $2,095 to $2,170 a month starting with January 2027 payments, about $75 more, and an average aged couple from $3,238 to $3,355; SSI recipients get the increase with the December 31, 2026 payment. About 487,611 Utahns received Social Security in December 2025, including 373,883 retired workers averaging about $2,168 a month, so 3.6% is roughly $35 million a month more for Utah households. The 2027 Medicare Part B premium has not been announced (it is $202.90 in 2026), but the hold-harmless rule keeps most retirees' premium increase from exceeding their COLA in dollars. Plus the 2027 earnings test ($25,560), taxable maximum ($192,300) and maximum benefit, how Utah's Social Security Benefits Credit phases out above $54,000 single or $90,000 joint, why a Utah Retirement Systems pension gets its own 4% or 2.5% capped COLA, and a Layton couple's 2027 checklist.
Read →
Utah Medicare Advantage Star Ratings 2027: What Changed
CMS published the 2027 Medicare star ratings on October 8, 2026, a week before Open Enrollment. Of the 13 Medicare Advantage contracts offered in Utah for 2027, one is rated 5 stars, three are 4.5, five are 4, one is 3.5, one is 3 and two are not yet rated; 29 of the 33 plans open to anyone sit under a contract rated 4 stars or higher. Six contracts moved: Regence rose from 3.5 to 4.5 and two Humana contracts from 3.5 to 4, while Select Health and one Aetna contract went from 4.5 to 4. The only 5-star plan in Utah is an Institutional Special Needs Plan for nursing-facility residents in five counties, so the 5-star Special Enrollment Period is not a general switching window here. Among stand-alone Part D plans, Humana's three Utah plans jumped from 3 to 4.5 stars. Includes every contract's rating, September 2026 Utah enrollment and a 29-county table.
Read →
Does Medicare Cover Dialysis in Utah? (2026 Costs & ESRD)
Yes, and at any age. Permanent kidney failure (End-Stage Renal Disease) qualifies a person for Medicare before 65, and Part B pays 80% after the $283 deductible in 2026 for generally three dialysis treatments a week in a center or at home, plus training, equipment, supplies, most dialysis drugs and the kidney doctor's monthly fee. Coverage usually starts the first day of the fourth month of dialysis, as early as the first month with home dialysis training, and can be backdated up to 12 months; for people entitled only through kidney failure it ends 12 months after dialysis stops or 36 months after a transplant, after which a drug-only benefit covers anti-rejection drugs for $121.60 a month. The 20% is the hard part: at Medicare's 2026 base rate of $281.71 a treatment, 156 treatments a year plus the kidney doctor's fee at the 2024 Utah average of $335.74 a month is about $47,976 in approved charges and about $9,595 at 20%, with no yearly cap in Original Medicare. Fewer Utahns are on dialysis than the national average: 1,113 Utahns in Original Medicare had dialysis in 2025, 0.46% of fee-for-service beneficiaries against 0.62% nationally, with San Juan County at 2.20%, and 21.0% of Utah's monthly dialysis physician billing was for home patients against 15.3% nationally. Plus every service in one covered-or-not table, the start-date rules, the 30-month employer-plan coordination period, how Medigap Plan G, Medicare Advantage out-of-pocket limits and Medicaid each handle the bill, why Medigap is hard to buy before 65, Utah's 53 Medicare-certified dialysis facilities and 750 stations by county and town (14 of 29 counties have one), which offer peritoneal dialysis and home hemodialysis training, their CMS star ratings, and a Provo example of one year of dialysis under three kinds of coverage.
Read →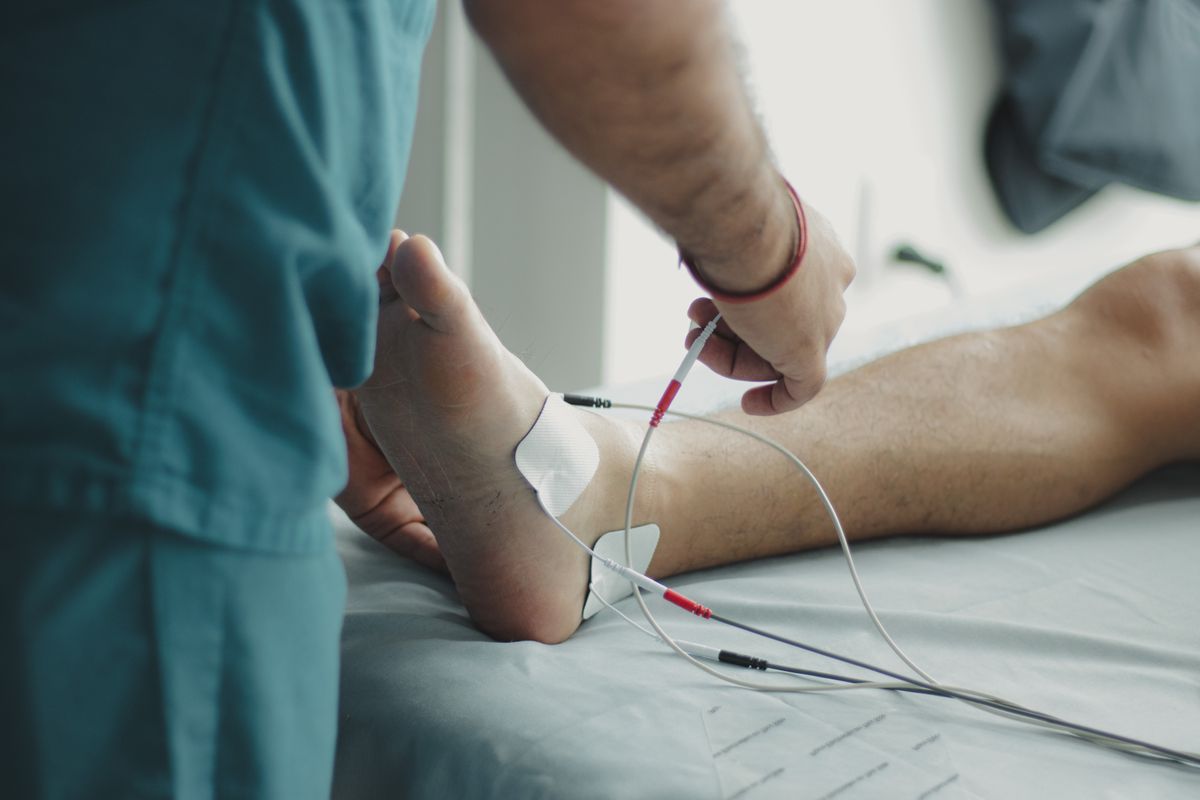
Does Medicare Cover Podiatry & Foot Care in Utah? (2026)
Yes for foot problems, mostly no for foot upkeep. Medicare Part B pays 80% after the $283 deductible in 2026 for a podiatrist to treat a foot injury or disease, such as hammer toe, bunions, heel spurs, ingrown nails, ulcers and infections; routine nail trimming, corn and callus removal and hygienic care are excluded unless a systemic condition such as diabetes, peripheral vascular disease or a peripheral neuropathy causes severe circulation problems or loss of feeling, or thick fungal nails cause pain or infection, and the findings are documented. At 2024 Utah averages a six-or-more-nail debridement had a Medicare-approved amount of $41.87 ($8.37 at 20%), paring two to four calluses $75.69, and ingrown toenail surgery $134.70; four visits a year for nails and calluses are $470.24 approved, $94.05 with the deductible met or $320.45 without. People with diabetes and loss of protective sensation get a foot exam every six months, and those with severe diabetic foot disease one pair of therapeutic shoes and three pairs of inserts a year (1,094 Utahns in 2024, at $85.77 a shoe). Utah uses podiatry about as much as the nation: 29,009 Utahns in Original Medicare had a podiatry claim in 2025, 10.88% of fee-for-service beneficiaries against 11.19% nationally. Plus every service in one covered-or-not table, the cost of each foot care code, use in all 29 counties (Washington, Cache, Iron and Carbon highest; Grand, San Juan and Duchesne lowest), 167 Utah podiatrists in 50 towns with 95% accepting assignment, why arch supports and flat-foot care are not covered, how Medicare Advantage copays and routine foot care allowances and Medigap Plans G and N each handle the bill, and a Logan example of two neighbors with the same toenails.
Read →
Does Medicare Cover Chiropractic Care in Utah? (2026 Costs)
Yes, but only one service. Medicare Part B covers a chiropractor's hands-on adjustment of the spine to correct a subluxation at 20% after the $283 deductible in 2026; the exam, X-rays, massage, traction and anything else a chiropractor furnishes or orders are not covered, and the same X-ray is covered when a medical doctor orders it. At 2024 Utah averages the usual three-to-four-region adjustment had a Medicare-approved amount of $37.39 against an average billed charge of $70.95, so a visit is about $7.48 at 20% and ten adjustments are $74.78 with the deductible met or $301.18 without. There is no visit cap, but Medicare pays only while the adjustments are active treatment with a reasonable expectation of improvement; once you are stable, further care is maintenance therapy, which CMS's manual says is not covered, the reverse of the rule for physical therapy. Utah uses the benefit a little less than the nation and less each year: 8,303 Utahns in Original Medicare had a chiropractic claim in 2025, 3.12% of fee-for-service beneficiaries against 3.37% nationally, down from 10,517 and 4.01% in 2021 while physical and occupational therapy nearly doubled, and Utah patients average 8.5 adjustments a year against 10.3. Plus every service in one covered-or-not table, the cost of each adjustment code, use in 28 counties (Grand, Piute, Kane and Washington highest; Salt Lake, Duchesne and Carbon lowest), 303 Utah chiropractors in 80 towns with 81% accepting assignment against 94% of physical therapists, how the Advance Beneficiary Notice works, how Medicare Advantage copays and routine-visit allowances and Medigap Plans G and N each handle the bill, and an Ogden example of a strained back.
Read →
Does Medicare Cover Physical Therapy in Utah? (2026 Costs)
Yes. Medicare Part B pays 80% of medically necessary outpatient physical, occupational and speech therapy after the $283 deductible in 2026, with no cap on visits or dollars in a year; therapy at home under the home health benefit is $0, a skilled nursing stay after a three-day inpatient hospital stay is $0 for 20 days and $217 a day for days 21 to 100, and physical therapy by telehealth is covered through December 31, 2027. The $2,480 figure is a documentation threshold, not a limit: the therapy caps were repealed in 2018, and above $2,480 of approved charges the therapist adds a KX modifier attesting the care is still necessary and keeps billing, which at Utah averages is an evaluation plus about 25 visits. At 2024 Utah averages an evaluation was $94.78 ($18.96 at 20%) and a typical hour-long visit of four 15-minute units $93.64 ($18.73), so an evaluation plus 12 visits is $1,218.46: $243.69 with the deductible met, $470.09 without. Utah uses therapy more than the nation and the gap is widening: 32,544 Utahns in Original Medicare had outpatient physical or occupational therapy in 2025, 12.20% of fee-for-service beneficiaries against 9.72% nationally (1.26 times the national rate), up from 7.27% in 2020, with billing providers up from 425 to 1,040; on the 2024 claims file 29,100 Utahns had therapeutic exercise, 15.86% of everyone with Part B in Original Medicare against 10.86% (1.46 times), and Utah runs above the nation on every physical therapy code but in shorter courses (18.2 units per person vs. 21.1). Medicare also covers therapy to maintain function or slow decline when a therapist's skill is needed; CMS's Jimmo settlement says coverage does not turn on the potential for improvement. Plus the rules and 2026 cost-sharing for every setting in one table, the cost of each therapy code, all 29 counties' therapy use and mobility-disability rates (Summit, Wasatch, Washington and Cache highest; Juab, Beaver, Duchesne, Kane and Carbon lowest), 1,132 Utah private-practice physical therapists with 94% accepting assignment and listings in 101 towns including Moab, Blanding, Vernal, Price, Richfield and Kanab, how Medicare Advantage copays, networks and prior authorization and Medigap Plans G and N each handle the visits, and a St. George example of a fall in January.
Read →
Does Medicare Cover PSA Tests in Utah? (2026 Costs)
Yes. Medicare Part B pays for a screening PSA blood test every 12 months for every man over 50, starting the day after the 50th birthday, with no deductible, no coinsurance and no upper age limit, because the screening PSA is paid under the clinical laboratory fee schedule; a diagnostic PSA is a lab test too and also costs nothing, and CMS's 2024 claims file shows Medicare paid 100% of the approved amount on all 6,845 Utah screening PSAs ($18.85) and 9,534 diagnostic ones. The yearly screening rectal exam is covered at 20% after the deductible but is almost always bundled into the office visit (only 11 Utah claims in 2024). What costs money is what a high result sets in motion, at 20% after the $283 Part B deductible: a first urology visit ($150.93 at 2024 Utah averages), a prostate MRI ($219.61 at an imaging center), and a biopsy that cost about $383.80 in a urologist's office ($77 to you) or about $1,832.95 in a hospital outpatient department, where the facility fee alone averaged $1,672.81 ($367 to you), before pathology at $56.44 a specimen. Utah men on Medicare test less than the nation: 3.73% of everyone with Part B in Original Medicare had a screening PSA against 5.03% nationally, 0.74 times the national rate, roughly 8% of men against 11%, while Utah runs 1.52 times the national rate for radical prostatectomy and 4.73 times for brachytherapy seeds. Utah has more prostate cancer than the nation (129.6 vs. 119.9 new cases per 100,000 men, 16th highest and rising 2.2% a year; 734.7 vs. 644.4 among men 65 and older), finds a smaller share late (20.4% vs. 22.5%), and still has a higher death rate (21.5 vs. 18.9; 160.4 vs. 138.9 among men 65 and older, 5th highest). Plus every covered test and its frequency in one table, Medicare's age-50-with-no-limit rule against the Task Force's talk-first-and-not-after-70 advice, the 2026 cost of each step from the blood test to surgery, seeds and hormone injections, all 29 counties' incidence, late-stage and death rates (Davis, Weber, Cache, Tooele and Utah counties highest; Salt Lake below the nation), 88 Utah urologists with 97% accepting assignment and the towns with none, how Medicare Advantage copays and prior authorization and Medigap Plans G and N each handle the bills, and a Layton example of a PSA that led to a biopsy.
Read →
Does Medicare Cover Mammograms in Utah? (2026 Costs)
Yes. Medicare Part B pays for a screening mammogram every 12 months for every woman 40 and older, 3D included, with no deductible and nothing to pay, no doctor's order and no upper age limit, plus one baseline mammogram at 35 to 39; CMS's 2024 claims file shows Medicare paid 100% of the approved amount on all 30,381 Utah screening mammograms, 97.1% of them in 3D. What costs money is what follows: a diagnostic mammogram, ultrasound, MRI or biopsy is an ordinary Part B service at 20% after the $283 deductible, and at 2024 Utah averages a call-back work-up (diagnostic mammogram with 3D plus a limited ultrasound) was $252.95 in approved charges, $50.59 at 20% but the whole amount if the deductible is not yet met, while an ultrasound-guided biopsy cost about $319 in a hospital outpatient department ($141.88 radiologist plus a $1,451.00 facility fee) and about $81 in an imaging office. Utah women on Medicare screen less than the nation: 16.56% of everyone with Part B in Original Medicare had a screening mammogram in 2024 against 20.35% nationally, 0.81 times the national rate, roughly 31% of women against 37%, and the CDC puts Utah women 50 to 74 at 72.1% screened in two years against 76.5%, with 28 of 29 counties below the national figure and San Juan, Duchesne, Grand and Uintah lowest. Utah has slightly less breast cancer than the nation (126.3 vs. 133.0 cases per 100,000 women) but finds 33.6% of it at a late stage against 30.7%, its death rate is higher (19.9 vs. 18.9; 99.1 vs. 90.2 among women 65 and older), and among women 65 and older incidence is now above the nation's and rising 2.2% a year. Plus every covered test and its frequency in one table, the 2026 cost of each test, the FDA's dense-breast letter and what Medicare does and does not cover for it, 73 FDA-certified Utah facilities by area including Moab, Blanding, Panguitch, Vernal, Price and Richfield, 466 Utah radiologists with 96% accepting assignment, all 29 counties' screening, cancer and late-stage rates, how Medicare Advantage copays and prior authorization and Medigap Plans G and N each handle the bills, and a St. George example of a screening that led to a biopsy.
Read →
Does Medicare Cover Colonoscopy in Utah? (2026 Costs)
Yes. Medicare Part B covers a screening colonoscopy at $0 with no minimum age, every 10 years at average risk or every 2 years at high risk, and also pays in full for a yearly stool test for blood, a multi-target stool DNA test or a blood-based test every 3 years for people 45 to 85, and, since 2025, a CT colonography. The catch is the polyp: if the doctor removes one during a screening colonoscopy, you pay 15% of the Medicare-approved amount to the doctor and 15% to the facility in 2026, with no deductible; that falls to 10% in 2027 and to nothing in 2030. At 2024 Utah averages and January 2026 facility rates, a screening colonoscopy that found a polyp cost about $166 in a surgery center and $251 in a hospital outpatient department, before the pathology bill; a clean one cost $0 everywhere, and CMS's own claims file shows Medicare paid 100% of the approved amount on every Utah screening colonoscopy and its anesthesia. Utahns on Medicare screen at or above the national rate: 3,957 Utahns in Original Medicare had a colonoscopy billed as a screening in 2024, 2.16% of everyone with Part B in Original Medicare against 1.80% nationally, and at least 10,289 had a colonoscopy of some kind, while the CDC's survey of adults 45 to 75 puts Utah's up-to-date share at 63.1% against 66.3% nationally, with 25 of 29 counties below the national figure and Uintah, Duchesne and Tooele lowest. Utah has the lowest colorectal cancer rate of any state, 30.4 new cases per 100,000 against 36.9 nationally and 116.6 against 152.7 among people 65 and older, yet 60.3% of Utah cases are still found at a late stage, the same as the nation, which is the argument for the test. Plus every covered test and its frequency in one table, the cost of a colonoscopy with and without a polyp in both settings for 2026, 2027 and 2030, all 29 counties' screening and cancer rates, 121 Utah gastroenterologists by city with 117 accepting assignment, how Medicare Advantage networks and referrals and Medigap Plans G and N each handle the bill, and a Logan example.
Read →
Does Medicare Cover Knee & Hip Replacement in Utah? (2026)
Yes. Medicare covers total knee and hip replacement when it is medically necessary, and which part pays depends on one line in the hospital: as an inpatient, Part A pays the hospital after the $1,736 deductible in 2026 and Part B pays the surgeon at 20%; as an outpatient, which most Utah joint replacements now are, Part B pays both and the hospital copay is capped at that same $1,736. Utahns use the benefit more than almost anyone: CMS's 2024 claims show 5,288 Utahns in Original Medicare had a total knee (3,443) or total hip (1,845) replaced, 2.88% of everyone with Part B in Original Medicare against 1.66% nationally, 1.79 times the national knee rate and 1.63 times the hip rate, and knee volume is up 8.8% in two years. The 2024 Utah average surgeon's fee was $1,572.50 for a knee ($314.50 at 20%) and $1,310.03 for a hip. The facility is the big bill: Medicare's January 2026 rate is $12,665.27 in a hospital outpatient department (your share capped at $1,736) and $9,393.16 for a knee in a surgery center ($1,878.63 at 20%, no cap), so all three settings cost an Original Medicare patient without Medigap about $2,000 to $2,200 before therapy. Inpatient is now the exception: at most 613 of Utah's 5,288 joint replacements (12%) were inpatient stays, against 15% nationally, and inpatient discharges fell 11% in a year, which is why a skilled nursing facility afterward, which needs a three-day inpatient stay, is rarely covered and home health, paid in full, is the usual route home. Plus the 14 Utah hospitals with the most inpatient joint replacements and what Medicare paid each, the three Utah hospitals (Castleview in Price, St. George Regional, Ashley Regional in Vernal) in CMS's mandatory TEAM model from January 2026, 264 Utah orthopedic surgeons by city with 94% accepting assignment, arthritis rates for all 29 counties, physical therapy at 20% with no annual cap, walkers, Medicare Advantage prior authorization and copays, Medigap Plans G and N, and a St. George example of one knee with the patient home the next morning.
Read →
Does Medicare Cover Cataract Surgery in Utah? (2026 Costs)
Yes. Medicare Part B covers cataract surgery with a conventional lens implant when it is medically necessary, and after the $283 deductible in 2026 you pay 20% of the Medicare-approved amount to the surgeon and 20% to the facility; it also pays for one pair of eyeglasses with standard frames after each surgery, the only time Medicare buys glasses. In Utah it is more common than almost anywhere: CMS's 2024 claims file shows 8,104 Utahns in Original Medicare had a standard cataract surgery, 4.42% of everyone with Part B in Original Medicare against 3.07% nationally, 1.44 times the national rate, with the YAG laser touch-up for a clouded capsule afterward at 2.33% against 1.71%. The surgeon's fee is the small bill: the 2024 Utah average Medicare-approved amount was $670.36, about $134 at 20%. The facility is the big one, and the building decides it: Medicare's January 2026 rate is $1,255.73 in an ambulatory surgery center ($251 at 20%) and $2,337.32 in a hospital outpatient department ($467), and in 2024 about a third of Utah's cataract patients (2,599) had the operation in a hospital, where the average Utah facility charge Medicare approved was $2,083.92. A multifocal or toric lens is an uncovered upgrade under CMS Ruling 05-01, no Medigap policy or Medicare Advantage plan pays it, and by rule no one may require you to choose it. The glasses benefit goes mostly unused: 358 Utahns got Medicare-covered frames in 2024, 4.4 per 100 surgeries against 8.8 nationally, because the optical shop must be a Medicare-enrolled supplier. Plus the CDC's finding that Utah seniors have cataracts at the national rate but get them treated more often (20.44% treated vs. 19.10%), vision disability for all 29 counties, 203 Utah ophthalmologists by city and assignment status (198 accept assignment), how Medicare Advantage copays, networks and prior authorization and Medigap Plans G and N each handle the bills, and an Ogden example of two eyes in one autumn.
Read →
Does Medicare Cover Skin Cancer Checks in Utah? (2026)
Medicare covers skin cancer, but it does not cover looking for it. A routine, no-symptoms skin screening is not on Medicare.gov's list of preventive services, because the U.S. Preventive Services Task Force rates visual skin examination of adults without symptoms as 'I' (insufficient evidence), and the yearly Wellness visit is a conversation, not a physical exam. The moment there is a reason, a changing or bleeding spot, a prior skin cancer, a referral, the visit, biopsy, pathology, freezing of precancerous spots, Mohs surgery, excision, light therapy, radiation and the repair are all Part B services at 20% after the $283 deductible in 2026. That line matters more in Utah than anywhere: the NCI and CDC registry puts Utah's melanoma rate at 43.8 new cases per 100,000 a year, first in the nation and 1.84 times the U.S. rate, and 185.1 per 100,000 among people 65 and older against 100.7 nationally, with Washington County at 335.3 and rising 11.4% a year. CMS's 2024 claims file shows the result: 23.4% of Utahns in Original Medicare had a precancerous lesion destroyed (15.4% nationally), 11.8% had a skin biopsy (9.8%) and 4.16% had Mohs surgery on the head, neck, hands or feet (2.56%). At Utah office averages a first biopsy was $79.44, a first Mohs stage $551.85 and a flap repair of the nose $707.62, so one basal cell carcinoma on the nose came to about $1,781.81 in approved charges and $356.36 at 20%. CMS lists 168 dermatologists with a Utah practice location, 161 of whom accept assignment; the other seven can charge up to 15% more, which Medigap Plan G pays and Plan N does not. Plus every Utah county's melanoma rate, dermatologists by city, how Medicare Advantage referrals and copays compare with a Medigap policy, and a St. George example.
Read →
Medicare C-SNPs in Utah for 2027: Diabetes & Heart Plans
A Chronic Condition Special Needs Plan, or C-SNP, is a Medicare Advantage plan that CMS lets limit its membership to people with specific severe or disabling chronic conditions and build its benefits, network, drug list and care coordination around them. For 2027 Utah has five, up from three, and every one of them serves the same CMS condition group: diabetes, chronic heart failure and cardiovascular disorders, a category CMS limits to cardiac arrhythmias, coronary artery disease, peripheral vascular disease and chronic venous thromboembolic disorder. You need only one of those diagnoses to qualify; high blood pressure or high cholesterol alone does not. CMS's new plan file lists all five at a $0 plan premium, which is not free: the Part B premium ($202.90 in 2026) and the plan's copayments still apply, and in-network out-of-pocket limits run from $5,500 to $9,850, with one plan at the federal ceiling. Matching CMS's September 2026 enrollment file, at least 17,329 Utahns were already in a C-SNP, about 6.7% of the state's Medicare Advantage members against 6.1% nationally, and 99% of them were in a single 25-county plan whose out-of-pocket limit rises from $5,200 to $5,500 and whose drug deductible goes from $440 to $685. Twenty-six of 29 counties have at least one C-SNP for 2027; Davis, Salt Lake, Utah and Weber have all five, 15 counties have exactly one, and Daggett, Piute and Wayne have none, though all three are among the five Utah counties where the CDC's adult diabetes rate exceeds the national 12.0%. Plus the 15 qualifying conditions, how the plan verifies your diagnosis with your doctor and what happens if it cannot by the end of the first month, the year-round Special Enrollment Period for people with a qualifying condition, why a Medigap holder should think twice, a seven-step comparison, and a St. George example of one plan and two patients.
Read →
Medicare Part D Plans in Utah for 2027: All 8 Compared
Utah retirees in Original Medicare have eight stand-alone Part D drug plans to choose from for 2027, down from ten, and the same eight are sold in every county. CMS's new plan file shows monthly premiums from $5.30 to $238.00, a spread of $2,792.40 a year, and deductibles from $300 to the new $700 maximum; every plan caps out-of-pocket spending on covered drugs at $2,400. Of the seven plans offered in both years, five raised the premium and two lowered it. The plan that charged $0.00 in 2026 is $30.60 a month in 2027, and the highest-premium plan goes from $132.60 to $238.00. Matching the list to CMS's September 2026 enrollment file, 43,368 Utahns are in a plan whose premium rises, 36,072 are in one whose premium falls, and 18,456 are in a plan ID that is not in the 2027 file. If everyone in a continuing plan stays put, the average premium that group pays goes from $30.58 to $48.14 a month, against a national projection of less than a dollar. For people with Extra Help, the regional benchmark rises from $37.60 to $45.51 but the number of $0-premium plans falls from three to two, and the third had 14,618 Utah members. Plus every plan in one table, basic versus enhanced explained, why the lowest premium is not always the lowest cost, all 29 counties, a seven-step comparison before December 7, and a St. George example.
Read →
Utah Medicare Advantage Plans for 2027: What's Changing
CMS published the 2027 plan list on September 28, 2026, and Utah's headline is calm: 51 Medicare Advantage plans against 55 this year, and an average monthly premium of $9.16 against $9.59. Underneath, more changed. Of the 51, 33 are open to general enrollment, down from 38, and 18 are Special Needs Plans. Twenty-four of the 33 list a $0 plan premium, which is not the same as free: you still pay the Part B premium and cost-sharing. The median in-network out-of-pocket limit rises from $5,800 to $6,700 and the lowest on the menu from $3,500 to $4,700, as the federal ceiling goes from $9,250 to $9,850. Of 31 plans offered in both years, 22 kept the same premium, 18 raised the out-of-pocket limit, and 22 of the 25 with drug coverage raised the drug deductible. County by county, 16 of 29 counties have fewer general-enrollment plans and 9 have more: Iron goes from 20 to 12, Morgan from 24 to 16, Box Elder from 18 to 12, and Wayne County loses its only one, leaving Wayne and Daggett with Special Needs Plans alone. Two insurers pull back to four and five counties, one leaves the Medicare Advantage market in Utah, and five counties have a single organization behind every plan. Matching CMS's September 2026 enrollment file, about 49,525 Utahns are in a plan ID that is not listed for their county in 2027; many will be moved to another plan from the same company, and the plan's letter says which. Stand-alone Part D plans drop from 10 to 8, with premiums from $5.30 to $238.00. Plus all 29 counties in one table, what to read first in the Annual Notice of Change, every deadline through March 31, and a Cedar City example.
Read →
Does Medicare Cover Ambulance Rides in Utah? (2026 Costs)
Yes — Part B covers ambulance transportation when traveling any other way could endanger your health, and after the $283 deductible in 2026 you pay 20% of the Medicare-approved amount, not 20% of the bill. CMS’s booklet is blunt: all ambulance companies must accept the Medicare-approved amount as payment in full. Medicare pays only to the nearest appropriate facility, covers a helicopter or airplane only when ground transport cannot do the job, and requires a doctor’s written order for non-emergency trips; repeated scheduled rides fall under a prior authorization program that reached Utah on August 1, 2022. Then the Utah data. In 2024, Utah suppliers billed Original Medicare an average of $2,338.33 for an advanced life support emergency transport and Medicare approved $519.64 plus $9.55 a mile, so a typical 11.6-mile trip was approved at about $630 and cost the patient about $126. The average Utah helicopter transport was billed at about $40,321, approved at about $8,261 and cost the patient about $1,652; a State of Utah report counted 1,632 air ambulance flights billed to non-Medicare coverage in 2024 at an average of about $50,784. Utahns on Medicare use ambulances less than the nation: 6.34% of those in Original Medicare in 2025 against 9.48% nationally, with routine non-emergency trips at 21.8 per 1,000 against 105.6. County shares run from 2.95% in Kane to 8.24% in Piute, and Medicare paid $770 per user in Salt Lake County but $1,535 in Wayne. Plus all 29 counties, 13 critical access hospitals and the transfer rules, why claims get denied, how Medicare Advantage and Medigap each handle the 20%, and a Vernal example of one emergency and two ambulances.
Read →
Medicare Vaccines in Utah (2026): Shingles, Flu, RSV, COVID
Every adult vaccine the CDC recommends is covered by Medicare at $0 in 2026, but which part of Medicare pays decides where you get the shot and whether you are covered at all. Part B pays for exactly four — flu, COVID-19, pneumococcal and hepatitis B — with nothing due when the provider accepts assignment. Everything else, including the two-dose shingles series, the RSV vaccine that Medicare.gov says adults 75 and older should ask about, and the routine Tdap booster, is a Part D vaccine, and since January 1, 2023 a Part D plan cannot charge a copayment or apply its deductible ($615 in 2026, $700 in 2027) to any ACIP-recommended vaccine. No Part D, no coverage: a Medigap policy has no drug benefit, and in 2024 the average Part D cost per Shingrix claim in Utah was $189.82. Then the Utah data. In 2024, 72,258 Utahns in Original Medicare had a flu vaccine billed to Part B, 39.4% against 40.7% nationally, and 94.3% of those flu vaccines were the high-dose or adjuvanted formulations made for people 65 and older; 48,353 had a COVID-19 vaccine and 11,794 a pneumococcal vaccine. Under Part D, 19,012 Utahns filled 24,836 Shingrix claims at a total drug cost of about $4.7 million and recorded beneficiary cost-sharing of $0, and 24,388 got an RSV vaccine. CDC surveys put Utah seniors above the national rate for shingles (61.0% vs. 55.9%), pneumococcal (71.9% vs. 70.3%) and Tdap vaccination, but below it for flu (60.1% vs. 63.8% in 2024–25, down from 75.6% in 2020–21). Plus why a doctor's office may not be able to bill your Part D plan, how Medicare Advantage and Medigap each handle vaccines, and a St. George example of a fall of four shots.
Read →
Does Medicare Cover Therapy in Utah? Mental Health (2026)
Yes — Part B pays 80% of the Medicare-approved amount for counseling and psychiatry after the $283 deductible in 2026, and the list of providers Medicare will pay is longer than most people think: psychiatrists, clinical psychologists, clinical social workers, nurse practitioners, physician assistants, clinical nurse specialists and, since January 1, 2024, marriage and family therapists and mental health counselors. Between weekly therapy and a hospital sit two covered steps, intensive outpatient programs (at least 9 hours a week) and partial hospitalization (at least 20), and inpatient care follows ordinary Part A costs with one special limit: 190 lifetime days in a freestanding psychiatric hospital. Through December 31, 2027, psychotherapy by telehealth is covered from anywhere in the U.S., including your home. Then the Utah data: in 2025, 4.40% of Utahns in Original Medicare used psychotherapy against 5.34% nationally, and in 2024 Utah providers billed about 27% fewer individual therapy sessions per 1,000 people with Part B, even though the CDC estimates depression among adults above the national 20.2% in every Utah county. Davis County has the state’s highest estimate, 28.9%, and only 3.78% psychotherapy use; ten counties had no provider treating more than ten local Medicare patients. The average Medicare-approved amount for a one-hour session in Utah was $117.17, so the 20% share was about $23.43. Plus how Medicare Advantage networks and Medigap each handle therapy, a Layton example, and why the hard part is usually finding an enrolled counselor.
Read →
Medicare & Medical Equipment in Utah (2026): Oxygen, CPAP
Part B pays 80% of a walker, a wheelchair, a hospital bed, a CPAP machine or a home oxygen concentrator after the $283 deductible in 2026 — but each follows a different clock, and the supplier decides whether 20% is really all you pay. Inexpensive items such as canes and walkers are bought; wheelchairs, hospital beds and CPAP machines are rented for 13 months and then become yours; oxygen equipment is rented for 36 months, the supplier must keep furnishing it for 24 more, and the cycle restarts after 5 years. Medicare pays only for equipment from an enrolled supplier, and only one that accepts assignment is limited to the deductible and coinsurance — CMS’s booklet lists five questions to ask before anything is delivered. Then the Utah data: in 2024, 13,706 Original Medicare beneficiaries referred by Utah providers rented a home oxygen concentrator, 74.7 per 1,000 with Part B against 27.8 nationally, about 2.7 times the national rate, while Utah ran below the nation on wheelchairs and hospital beds. The average Medicare-approved monthly rental was $120.04 for a concentrator and $46.40 for a CPAP machine, so the 20% share was about $24 and $9 a month. Plus DME use and supplier counts for all 29 Utah counties in 2025 beside CDC COPD estimates, how Medicare Advantage and Medigap each handle equipment, a Cedar City hip-fracture example, and why the equipment bill is tens of dollars while the care around it is thousands.
Read →
401(k) Rollover at Retirement in Utah (2026): Roll It, Leave It, or Cash It Out
Four doors open when you leave a Utah employer — leave the plan alone, move it to a new employer's plan, roll it to an IRA, or take the cash — and only one of them is hard to undo. The rule that costs people the most is the plainest one the IRS publishes: a retirement plan distribution paid to you is subject to mandatory withholding of 20%, even if you intend to roll it over later. Withholding does not apply in a direct rollover, and a check made payable to the receiving plan or IRA is not subject to it either. Once the money is in your hands the clock is 60 days, and to keep the whole taxable amount deferred you must use other funds to make up for the amount withheld — so on a $100,000 distribution, $20,000 is withheld, $80,000 arrives, and rolling only what arrived turns $20,000 into taxable income for the year. Then the features that live inside an employer plan and do not travel: a participant who is not a 5% owner can delay required minimum distributions until the year they actually retire, while an IRA requires them at the applicable age (73, or 75 for people reaching age 74 after 2032) even if you are still employed; the age-55 separation-from-service exception to the 10% additional tax belongs to the plan; net unrealized appreciation on employer securities, reported in box 6 of Form 1099-R, is generally untaxed until you sell the shares and is lost on a rollover; and distributions from a governmental 457(b) plan — the URS 457(b) that Utah teachers, city workers and state employees hold — are not subject to the 10% additional tax at all, except for amounts rolled into it from another plan or IRA. Plus the distributions that cannot be rolled over (an RMD among them, at a 6% annual cost if it lands in an IRA anyway), the IRA one-rollover-per-year limit, the $1,000 and $5,000 thresholds at which a plan can move or cash out your account without consent, and why Utah Code 78B-5-505 — which lists 401(k), 403(b), 457, 408 and 408A together — makes the usual creditor-protection tiebreaker weaker here than elsewhere.
Read →
Selling a Life Insurance Policy in Utah (2026): How a Life Settlement Works and the Rules That Protect You
A great many Utah households are paying premiums on a policy nobody needs anymore, at exactly the moment a care bill arrives — and the choice looks binary: keep paying, or stop paying and get nothing. There is a third door, and Utah Code Title 31A, Chapter 36 regulates it closely. A life settlement is the sale of an existing policy to a licensed buyer, and the statute counts the agreement as one even if it is marketed as a “viatical settlement” or a “senior settlement.” It explicitly does not include a loan or an accelerated death benefit paid by your own insurer under the terms of the policy — which is why Utah Admin. Code R590-222-8(1)(a) forces the buyer to disclose those in-policy alternatives first. The protections are unusually concrete: an unconditional right to rescind that ends 15 calendar days after the proceeds arrive; a settlement treated as rescinded if the insured dies in that window and the money is repaid within 60 days; a two-year ban on selling a newly issued policy unless you certify one of ten circumstances, from a terminal or chronic illness to a divorce, a retirement, a bankruptcy judgment or an unexpected income drop; twelve specific written disclosures before you sign the application, and a second disclosure at signing that must state the producer’s compensation and the method used to calculate it; escrow, with payment due three business days after the insurer acknowledges the ownership change and the settlement voidable for lack of consideration if that deadline is missed; and a producer who, regardless of who pays the commission, represents only you and owes you a fiduciary duty. Then the tax half, which most older articles still get wrong: section 13521 of the Tax Cuts and Jobs Act amended IRC section 1016(a) so basis is no longer reduced by the cost of insurance, and IRS Rev. Rul. 2020-05 reworked its own example accordingly — an $80,000 sale of a policy with $64,000 of premiums paid now produces $16,000 of income ($14,000 ordinary, $2,000 long-term capital gain) instead of $26,000, while a term policy sold at a loss flips from $19,750 of taxable income to a $25,000 long-term capital loss. With the state and federal definitions of terminally and chronically ill, the eight-step paperwork sequence and its deadlines, what a year of Utah care actually costs against the proceeds, and eight questions to bring to the appointment.
Read →
Fixed Indexed Annuities in Utah (2026): Caps, Participation Rates, and What the Best-Interest Rule Makes Your Agent Tell You
The pitch is market-linked growth with no market losses, and the first half is real: the NAIC’s buyer’s guide — the one the Utah Insurance Department publishes — says index-linked interest in a fixed indexed annuity is “guaranteed to never be less than zero, even if the market goes down.” What almost nobody explains is how little of a good year actually arrives. Three percentages stand between the index and your account, and the SEC works the arithmetic itself: a 75% participation rate turns a 10% index return into 7.5%; a 7% cap turns a 12% index return into 7%; a 3% spread turns 9% into 6%; and a contract carrying both a 75% participation rate and a 3% spread turns 10% into 4.5%. The SEC’s verdict on all three: they “reduce your return in the same way that a direct fee would even if the annuity is called a ‘no fee’ annuity.” Before any of that math runs, dividends usually come out — a 7% total-return year with 2.5% from dividends is treated as a 4.5% index return. And the cap itself is often not fixed: contracts “commonly allow the insurance company to change some of these features periodically.” Then the Utah half. Rule R590-230, effective December 8, 2023, requires an agent recommending an annuity to act in your best interest without putting their own or the insurer’s financial interest ahead of yours, and to hand you a pre-sale disclosure naming which of seven product types they are even licensed to sell, every source and type of compensation they will receive, the surrender period and charge, the potential tax penalty, limitations on interest returns, and every material conflict of interest — plus a written record of the recommendation and the basis for it. On a replacement, the agent must weigh a new surrender period, lost benefits, and whether you have exchanged another annuity in the preceding 60 months. With the monthly point-to-point design that can credit 0% in an up year, the six ways money still leaves a 0%-floor contract, what the rule explicitly does not require, the 5-year Treasury at 4.83% as the benchmark question, Utah’s 10-day (30-day on a replacement) examination period, and eight questions to bring to the appointment.
Read →
Medicare Annual Wellness Visit vs. Physical in Utah (2026)
Medicare pays for a yearly “Wellness” visit at $0 and pays nothing for a routine physical, and CMS tells doctors the physical is “prohibited by statute; patient pays 100% out-of-pocket.” The Wellness visit is a conversation, not an exam: a Health Risk Assessment, your history and medication list, blood pressure and weight, a cognitive screen, fall and daily-living risk, depression and substance-use screening, an offer to discuss advance directives, and a written checklist of the screenings and vaccines you are due for — once every 12 months, with the 2026 Part B deductible of $283 waived. The one way it becomes a bill is anything done in the same appointment that is outside the preventive benefit: treat a specific problem and that part is a normal office visit at 20% after the deductible; ask for a physical and you may owe the full amount. Then the Utah numbers from CMS claims data: 94,465 Utahns in Original Medicare had a yearly Wellness visit in 2024, 51.5% of those with Part B against 39.2% nationally, billed at an average $280.03 and paid by Medicare at about $120 with $0 from the patient, plus a county-by-county table of who goes in for a routine checkup at all, from 76.2% in Daggett County to 68.4% in Cache and Utah counties. With what Medigap and Medicare Advantage each do with the visit, an Ogden walk-through, and why the fall, memory and advance-directive questions in that visit are the start of a long-term care plan.
Read →
The Long-Term Care Insurance Elimination Period in Utah (2026): What the Waiting Period Really Costs
Every long-term care policy contains a number that decides how much of the first stretch of care is yours: the elimination period, a deductible measured in days rather than dollars. During it you qualify, you need care, you arrange care — and you pay for it. The Utah Insurance Department lists it among the elements every buyer should compare and states the trade-off plainly: longer elimination periods equal cheaper premiums. It is also the single most-confused number in the contract, because Utah Administrative Code R590-148-9(2) separately requires a qualified contract to condition benefits on a determination that you cannot perform the activities of daily living for an expected period of at least 90 days — a forward-looking medical judgment about qualifying, not a waiting period, and a policy can carry a 0-day elimination period and still require it. The six activities are fixed by R590-148-4(1): bathing, continence, dressing, eating, toileting and transferring. Then the arithmetic nobody runs. Using CareScout’s 2024 Utah monthly figures, a 90-day wait costs about $14,055 in assisted living, $20,592 for homemaker help, $21,735 for a home health aide, $25,095 in a semi-private nursing home room and $31,938 in a private one — and stretching the wait to 180 days to shave the premium doubles every one of those numbers. Medicare does not reliably fill the gap: Part A covers a skilled nursing facility stay only after a qualifying inpatient hospital stay of at least three days in a row, caps it at 100 days per benefit period, and in 2026 charges $0 a day for days 1–20 after the $1,736 deductible, $217 a day for days 21–100, and everything from day 101 — while paying nothing at all for the custodial care most policies are built for. Plus what R590-148-7 forces insurers to include in home care, why your certification cannot be rescinded mid-claim, the two questions about how days are counted that belong in writing, and a St. George example of the whole sequence.
Read →
Medicare Home Health Care in Utah (2026): Who Qualifies
Medicare will send a nurse or therapist to your home and pay the whole bill, but only when four things are true at once: a doctor or other allowed practitioner has certified that you need part-time or intermittent skilled nursing or therapy, you are homebound, a Medicare-certified agency delivers the care under a plan of care reviewed at least every 60 days, and a face-to-face encounter is on file. Medicare.gov’s price for covered home health services is $0, with 20% owed only on medical equipment. Homebound is not bedbound: leaving must be hard or not recommended and you normally stay in, but trips to the doctor, adult day care, church and the occasional haircut or family reunion are allowed. The limits are up to 8 hours a day of nursing and aide care combined and 28 hours a week (35 for a short stretch if ordered), and Medicare pays nothing for 24-hour care, meals, housekeeping, or bathing and dressing help when that is the only care you need. You do not have to be improving; the Jimmo settlement made skilled care to maintain your condition or slow decline a covered service. Then the Utah numbers: all 82 Medicare-certified agencies in the state with both CMS star ratings, completed patient surveys and “would definitely recommend” percentages, a state average of 3.5 quality stars against a national 3, 19,366 Utahns with Original Medicare (7.26%) who used the benefit in 2025 at $5,513 each across every county, and the fast appeal to Acentra Health at 888-317-0891 by noon the day before the date on the Notice of Medicare Non-Coverage.
Read →
Medicare Advantage HMO vs. PPO in Utah (2026 Guide)
Every Medicare Advantage plan sold in Utah for 2026 carries a suffix that matters more than its premium: (HMO), (HMO-POS) or (PPO). In an HMO, Medicare.gov says you generally must get your care from doctors and hospitals in the plan’s network, except for emergency care, out-of-area urgent care and temporary out-of-area dialysis; you usually choose a primary care doctor, need a referral to see a specialist, and if you go out of network on your own you may pay the full cost. In a PPO you pay less in network but can generally use any out-of-network provider who takes Medicare, at a higher cost share and with no referrals. An HMO-POS is an HMO with a short, listed out-of-network benefit, and Utah has an unusual number of them because UnitedHealthcare’s largest Utah contract is one, sold in 25 of 29 counties. The 2026 landscape tilts PPO in plan count — 26 of the 38 plans open to everyone are PPOs, 6 are HMOs and 6 are HMO-POS — but HMO in members: CMS’s August 2026 file puts 164,497 of Utah’s 271,278 Medicare Advantage enrollees (60.6%) in HMO or HMO-POS plans and 105,902 in local PPOs. The split is local. Salt Lake County is 59.6% HMO and Cache County 78.4%, while in Washington County PPO members outnumber HMO members, 13,724 to 11,632, and PPOs also lead in Iron, Grand, San Juan, Kane, Garfield and Rich counties. On the money: CMS caps a 2026 plan’s in-network maximum at $9,250 and a PPO’s combined in- plus out-of-network maximum at $13,900; Utah’s general-population PPOs carry in-network limits from $4,500 to $9,250 (median $5,900), HMOs from $5,000 to $6,700 (median $5,600), and all four PPOs at $8,900 or more are Part B give-back plans. Every county tabulated, the seven-question test for choosing a type, and the windows for switching: Open Enrollment October 15 to December 7, the January-to-March Medicare Advantage Open Enrollment Period, and the 12-month Medigap trial right.
Read →
1035 Exchange: Old Annuity to Long-Term Care (Utah 2026)
A great many Utah retirees hold a deferred annuity bought decades ago, never annuitized, worth far more than they put in — and no long-term care coverage at all. Cashing it out means the entire gain comes out first, taxed as ordinary income in a single year. Section 844(b) of the Pension Protection Act of 2006 opened a door: since exchanges occurring after December 31, 2009, IRC section 1035 has allowed a life insurance, endowment or annuity contract to be exchanged tax-free for a qualified long-term care insurance contract, with the old contract’s basis carrying over under IRC section 1031(d). IRS Notice 2011-68 sets out the rules, and the arrows run one way: value flows toward long-term care coverage and never back out of it. You cannot exchange an annuity into life insurance, you cannot exchange a long-term care contract into anything but another one, and nothing in section 1035 reaches an IRA or a 401(k). Partial transfers are generally allowed, which matters because premiums are paid over years — but the money must move insurer to insurer, since Revenue Ruling 2007-24 treats a check you endorse over as a taxable distribution. The trade-offs are real: Congress gave you the exclusion instead of the deduction, so a 1035-funded premium produces no medical expense deduction (the 2026 age caps run from $500 to $6,200 per insured person), and a qualified long-term care contract by definition has no cash surrender value. Against Utah medians of about $4,685 a month for assisted living and $10,646 for a private nursing home room, plus the ACL estimate that 70% of people turning 65 will need some care, that trade is often worth making — for the right person. Plus the nine-step Utah order of operations, the R590-93 replacement notice, the 30-day right to return, the $430 per diem cap, and who should skip this entirely.
Read →
Type I vs. Type II Assisted Living in Utah (2026)
Utah licenses assisted living under one short administrative rule, R432-270, and the whole thing turns on a single safety question: can the resident get out of the building in an emergency, and how much help does that take? A facility is licensed type I if its residents can exit without the assistance of another person, and type II if they can exit only with the limited assistance of one person. Everything else follows. A type I facility provides social care, and may not retain anyone who comes to need total assistance in more than three activities of daily living. A type II facility provides an array of coordinated supportive personal and health care services 24 hours a day, must have a registered nurse assess and monitor every resident rather than just handle medications, must keep at least one certified nurse aide on duty around the clock, and may keep a resident past the three-ADL line if staffing meets the need. Neither type may provide skilled nursing care, and neither may admit or retain a person who needs 24-hour continual nursing care expected to last more than 15 calendar days — the rule behind the phone call families never expect. A licensed health care professional must reassess every resident before admission and at least every six months, and the admission agreement must contain seven specific terms, including a 30-day notice before any rate change and the refund rules for an emergency transfer or a death. On money: Utah’s median assisted living cost was about $4,685 a month in the CareScout 2024 survey, against roughly $8,365 a month for a semi-private nursing home room; Medicare pays $0 toward either kind of custodial care, and Utah Medicaid’s New Choices Waiver can pay for the services in a type 1 or type 2 facility but, by the terms of its own provider contract, not for room and board. Plus the capacity classes, the three categories neither type may keep, eight questions to ask before signing, and who to call when something is wrong.
Read →
Medicare Advantage Star Ratings in Utah: 2026 Guide
Every fall, about three weeks before Medicare Open Enrollment, CMS publishes a 1-to-5 star rating for every Medicare Advantage and Part D contract in the country, and the Plan Finder shows those stars next to every plan a Utah retiree can choose. The 2026 ratings went live on October 9, 2025 and grade a drug-covering Medicare Advantage contract on up to 43 measures, from blood-sugar control and readmissions to how quickly members get appointments and how fast appeals are decided; the 2027 ratings are due in October 2026. Nationally, 40% of MA-PD contracts earned 4 stars or higher and 18 earned 5, with an enrollment-weighted average of 3.98, while stand-alone drug plans average just 3.01. In Utah, the CMS 2026 landscape file shows 15 Medicare Advantage contracts and 55 plans: four contracts rated 4.5 stars, one at 4.0, two too new to be rated, and none carrying CMS's low-performing icon. No 5-star contract serves any Utah county, which means the 5-star Special Enrollment Period, usable once between December 8 and November 30 where a 5-star plan exists, does not apply in Utah for 2026. Salt Lake and Davis counties each have 14 of 31 general-population plans rated 4 or higher; Washington County has 6 of 17; Wayne County has one plan and Daggett none outside Dual Special Needs Plans. Utah's ten stand-alone Part D plans rate between 2.0 and 3.5. The rating belongs to the contract, not the plan, so use it as a filter after you have checked the network, your drugs and the out-of-pocket maximum.
Read →
Medicare Advantage Prior Authorization in Utah (2026 Rules)
Every Medicare Advantage plan sold in Utah must cover everything Original Medicare covers. The sentence the marketing skips is the next one on Medicare.gov's own comparison page: you may need to get approval from your plan before it covers certain services or supplies, while in most cases Original Medicare needs no approval at all. Prior authorization is the plan's right to look at a request for an MRI, a rehab stay, a hospital bed or a course of physical therapy and say yes, no, or not yet, and the rules around it changed in two steps. Since January 1, 2024, plans must follow Medicare's national and local coverage determinations, keep an approval valid for the whole course of treatment, and give a new member a 90-day transition with no prior authorization for treatment already underway. Since January 1, 2026, under CMS-0057-F, a plan must decide a standard request within 7 calendar days and an urgent one within 72 hours, state a specific reason for every denial, and post its own approval and denial statistics online, with the first set due March 31, 2026 and an electronic prior authorization system due January 1, 2027. The HHS Office of Inspector General's sample of 250 denials from 15 large plans found 13% met Medicare's coverage rules and likely would have been approved under Original Medicare, most often for advanced imaging and post-acute stays. The appeal clock runs your way: 65 days to file, 30 days for the plan to answer (72 hours if your doctor says waiting is dangerous), and an automatic Independent Review Entity if the plan says no twice. It reaches most of the state: CMS's May 2026 enrollment file puts 268,675 of Utah's 488,797 beneficiaries, 55%, in Medicare Advantage-type plans, including 24,000 in Weber County and 27,323 in Davis County; Cache County, at 62.7%, is the most Advantage-heavy county and San Juan the least. All 29 counties tabulated, plus why the WISeR prior authorization pilot for Original Medicare does not run in Utah, and the seven things to do the day a denial letter arrives.
Read →
Medicare Advantage Plan Leaving Utah in 2027? Your Rights
Every fall a share of Utah's Medicare Advantage members open a Plan Non-Renewal Notice saying their plan will not exist next year. Medicare.gov's instruction is blunt: you must look for a new plan. What the letter does not spell out is that it also opens a door that is usually locked. Under federal law, a Medicare Advantage plan leaving Medicare gives you a guaranteed-issue right to buy Medigap Plan A, B, D or G (C or F if you were Medicare-eligible before 2020) from any Utah insurer with no health questions, as long as you return to Original Medicare: apply as early as 60 days before your coverage ends (November 1, 2026 for a plan ending December 31) and no later than 63 days after (March 4, 2027). Plan N is not on the federal list, and Utah's birthday rule does not cover this situation. You also get a Special Enrollment Period from December 8 to the last day of February on top of Open Enrollment (October 15 to December 7); do nothing and you land in Original Medicare on January 1 with no drug plan and a late-penalty clock ticking. It is not rare. Comparing CMS's 2025 and 2026 landscape files with the CMS 2026 Plan Crosswalk, nine Utah plans from Select Health, Aetna and Cigna were marked Terminated/Non-renewed for 2026, touching 81 county-plan combinations; Salt Lake, Davis, Weber, Tooele, Box Elder and Morgan each lost six 2025 plans while seventeen plan IDs arrived, including a new carrier. All 29 counties tabulated, plus a date-by-date timeline and a seven-step checklist for the week the letter arrives.
Read →
Medicare Insulin & Diabetes Costs in Utah (2026): $35 Cap
If you take insulin, the most important number on Medicare in 2026 is $35: Medicare.gov says the cost of a one-month supply of each Part B- and Part D-covered insulin product is no more than $35, with no deductible, even before you have met your plan's $615 Part D deductible and even if you get Extra Help. But insulin is one line on a diabetes budget. The meter, the strips, the continuous glucose monitor, the podiatrist, the retina exam, the therapeutic shoes and the self-management class each sit under a different Medicare rule, and most of them are Part B at 20% after the $283 deductible — while diabetes screenings, medical nutrition therapy and the Medicare Diabetes Prevention Program, which has 25 listed Utah locations, cost nothing when the provider accepts assignment. CMS's own survey found 31.8% of Medicare beneficiaries have been diagnosed with diabetes, 21% of those take insulin, 31.2% have had neuropathy and only about a third have ever completed the self-management course Medicare pays for. County by county, CDC PLACES puts diagnosed diabetes among Utah adults at 6.9% in Utah County and 8.5% in Salt Lake County, climbing to 10.7% in Washington County, 12.8% in Carbon County and 15.4% in San Juan County — we joined all 29 counties to CMS's May 2026 Medicare enrollment. Plus the seven diabetes drugs with negotiated Medicare prices (Januvia $113, Jardiance $197 and NovoLog $119 since January; Ozempic $274, Tradjenta $78 and Janumet $80 from January 1, 2027), why Ozempic for diabetes and Wegovy for weight run through two different doors now that the $50-a-month Medicare GLP-1 Bridge began July 1, 2026, what changes between Original Medicare and Medicare Advantage when you have diabetes, and six things to do before December 7.
Read →
Medicare Part D Changes for 2027 in Utah: Read Your ANOC
Sometime before the end of September, every Utah retiree with Medicare drug coverage gets a thick envelope titled Annual Notice of Change, and most of it gets set aside for a quieter week that never comes. This year the numbers inside are worth ten minutes, because the federal rules underneath every plan move more in 2027 than they did in 2026. CMS finalized the figures on April 6, 2026: the Part D deductible ceiling rises from $615 to $700 and the annual out-of-pocket cap from $2,100 to $2,400, both pushed up by a 13.65% annual percentage increase in per-person drug spending that the Inflation Reduction Act wrote into the indexing formula. On July 28 CMS set the 2027 national base beneficiary premium at $41.33, up from $38.99 — the full 6% the law allows — and announced it will end the Premium Stabilization Demonstration that had been limiting how far a stand-alone drug plan's premium could rise, “to return the program to operating under traditional market conditions in CY 2027.” The good news arrives the same day the higher cap does: on January 1, 2027, fifteen more drugs get negotiated Medicare prices, including Ozempic at $274 a month against a $959 list price, Trelegy Ellipta at $175 against $654, Linzess at $136 against $539, Breo, Tradjenta and Janumet at discounts of 83% to 85%, and oncology drugs like Xtandi, Ibrance and Calquence. About 5.3 million of the 53 million people with Part D filled one of them in 2024. In Utah the letter goes to 391,825 people with drug coverage — 140,690 in stand-alone plans, the group most exposed to the premium change, and 251,135 in Medicare Advantage plans with drug coverage — and roughly 52,600 of them receive Extra Help, whose 2027 copays move to $1.65 to $14.40 a prescription. Plus why the late enrollment penalty quietly rises with the base premium (a two-year gap goes from about $9.40 to $9.90 a month), the four lines in the ANOC that carry nearly all of the money, what a negotiated price does and does not do at the pharmacy counter, and six things to do between the letter and December 7.
Read →
Nursing Home Discharge Rights in Utah (2026): How to Appeal
A discharge notice from a nursing home rarely looks like a fight — it looks like a form handed over on a Tuesday saying the facility can no longer meet your mother's needs and she will be moving in thirty days. It is not a decision that has already been made. Federal law lets a facility transfer or discharge a resident for six reasons only, and 42 CFR 483.15(c)(1)(i) lists every one: her needs cannot be met there, her health improved enough that she no longer needs the services, she endangers the safety of others, she endangers the health of others, she failed to pay after reasonable and appropriate notice, or the facility is closing. Utah adopts the same standard at R432-150-22. Running out of Medicare days is not on the list; neither is switching from private pay to Medicaid. The notice must be written, must arrive at least 30 days ahead except in four narrow situations, must state the reason, the date, the destination and how to appeal — and the facility “must send a copy of the notice to a representative of the Office of the State Long-Term Care Ombudsman,” every time, which in Utah means sltcop@utah.gov or fax 801-532-2217. Utah publishes a discharge appeal form written for this exact situation; it goes to the DHHS Office of Administrative Hearings within 30 days of the notice, and while the appeal is pending the resident stays — including coming back from a hospital bed — unless the facility documents a real danger. What our own analysis of the CMS Health Deficiencies file found is the uncomfortable part: across Utah’s 97 certified nursing facilities and 8,379 beds, surveyors wrote 335 resident-rights citations since late 2019 but only 42 involving transfer, discharge or the required notices, at 31 facilities. Nationally, discharge complaints have been the ombudsman program’s most common complaint for a decade, and in Utah they ranked top-three two years running. Complaints in the hundreds, citations in the dozens. Plus why “Medicare stopped paying” is a different appeal with a noon-the-day-before deadline, the county-by-county ombudsman phone list, and the five things to do the day the notice arrives.
Read →
Medicare Part B Give-Back in Utah (2026): The Real Cost
Somewhere between the fourth and the fortieth mailer, every Utah retiree hears the pitch: a plan that puts money back in your Social Security check. It is not a scam and it is not a loophole — 42 CFR 422.266(b)(3) lets a Medicare Advantage plan credit its rebate dollars “toward reduction of the Medicare Part B premium,” which in 2026 is $202.90 a month, up from $185.00. What the mailers leave out is the price. We joined the CMS 2026 Plan Benefit Package file — which carries a field named literally “Premium Part B Reduction Amt” — to CMS August 2026 Utah enrollment data, and of the 50 individual-market Medicare Advantage plans with meaningful Utah enrollment, 14 include a give-back, from $1.00 to $184.70 a month. Sort those 14 by drug coverage and the pattern stops being subtle: all seven plans with no Part D give back between $30 and $100 a month, a median of $75, while four of the seven that do cover drugs give back $5 or less. A plan that never has to pay for your prescriptions has far more rebate money to spend somewhere visible. And you cannot simply take the money and buy Part D yourself — Medicare.gov is flat about it: join an HMO or a PPO without drug coverage and “you can’t get a separate Medicare drug plan.” Every one of Utah’s seven no-drug give-back plans is an HMO, HMO-POS, or PPO; not one is a PFFS or MSA plan, the only two types that leave the door open. So the real trade is $1,200 a year against three stacked costs: every prescription at full price, the loss of Part D’s $2,100 out-of-pocket cap for 2026, and a late enrollment penalty of 1% of the $38.99 national base premium per uncovered month — about $9.40 a month after two years, added for life. Plus the three groups a give-back is worth nothing to, why the regulation deliberately ignores your late enrollment penalty and your IRMAA surcharge, and the six things to check on Plan Finder before the number on the mailer decides anything.
Read →
Does Utah Have an Estate or Inheritance Tax? (2026)
Utah families ask it in this order: will the state take a cut, will the IRS, and — much later, much more quietly — what if Mom needs care for four years? The first two answers are short. Utah has no inheritance tax and no state estate tax: the Utah State Tax Commission says the tax “was repealed,” because Utah’s was a “pick up” tax that merely collected part of the federal credit for state death taxes, and federal changes “eliminated Utah’s inheritance tax after December 31, 2004.” No Utah return needs to be filed and no Inheritance Tax Waiver is required, so a bank asking for state inheritance tax clearance is twenty years out of date. The federal estate tax still exists, but the IRS basic exclusion for a 2026 death is $15,000,000 per person, up from $13,990,000 in 2025 — raised by the Working Families Tax Cuts Bill, signed July 4, 2025 as Public Law 119-21, which amended IRC § 2010(c)(3). A married couple can generally shelter $30,000,000, and the annual gift exclusion is $19,000 per recipient, unchanged from 2025. Which makes the third question the only one that matters for most Utah retirees. A private nursing-home room in Utah runs about $127,750 a year and assisted living about $4,685 a month (CareScout 2024), and about 70% of people turning 65 will need some long-term care, roughly 20% of them for longer than five years (Administration for Community Living). The expensive mistake is mixing the two rulebooks: the IRS may not tax a gift, but Medicaid.gov says applicants who need long-term services and supports “will be denied LTSS coverage if they have transferred assets for less than fair market value during the five-year period preceding their Medicaid application” — so checks written to grandchildren at 78 can be the reason Medicaid says no at 81. Gifting a long-held home carries a second, quieter cost, because property passing at death generally has its basis adjusted to date-of-death value while a lifetime gift generally does not. Plus the portability trap (the unused spousal exclusion is lost without a timely Form 706), Utah’s $100,000 small estate affidavit and why it cannot transfer a house, and the four things worth checking instead of estate tax.
Read →
Observation Status vs. Inpatient in a Utah Hospital (2026)
A parent falls in Sandy or Ogden or St. George, spends three nights in a hospital bed, goes to rehab — and three weeks later a bill arrives for the entire rehab stay. The explanation is one word nobody said out loud at the time: the hospital stay was observation, not an admission. Medicare draws the line at a doctor's order, not at a bed. In its own words, you are an outpatient if no doctor has written an order to admit you, “even if you spend the night in the hospital” — and while an admission is “generally appropriate when you're expected to need 2 or more midnights of medically necessary hospital care,” expecting two midnights is not the same as having the order. The expensive consequence is not the hospital bill. Medicare Part A covers skilled nursing care only after a qualifying inpatient stay of at least 3 days in a row, not counting the discharge day, and “time you spend at the hospital under observation or in the emergency room before you're admitted doesn't count toward the 3-day qualifying inpatient hospital stay, even if you're there overnight.” With a qualifying stay Medicare pays SNF days 1–20 in full, then $217 a day through day 100; without one you pay everything from day one — about $285 a day for a semi-private Utah room and $350 for a private one, roughly $5,700 or $7,000 for a 20-day rehab stay and $28,500 or $35,000 for a full 100 days. Utah has 91 Medicare-certified nursing facilities and 8,129 certified beds in only 19 of the state's 29 counties, so a self-pay stay in rural Utah is often far from home too. What is genuinely new: starting February 14, 2025, a patient admitted as an inpatient and then switched to observation gets a Medicare Change of Status Notice (CMS-10868) and the right to a fast appeal, decided in about two days by Utah's reviewer, Acentra Health, at 1-888-317-0891 — and if it succeeds, the SNF stay can qualify after all. The look-back door, meanwhile, has shut: effective January 2, 2026 the retrospective Alexander v. Azar appeal window ended, and late filings now need good cause. Plus the 36-hour MOON deadline and why it arrives too late to help, why your everyday blood-pressure pills are not covered under observation, when Medicare Advantage waives the 3-day rule, and the seven questions to ask before discharge.
Read →
Medigap Plan G vs. Plan N in Utah (2026): The Real Trade-Off
Once a Utah retiree picks Original Medicare plus a supplement, the shortlist is almost always two letters — and the choice is narrower than it is sold as. Medigap is standardized by federal law, so ten of the fourteen rows on the benefit grid are identical between Plan G and Plan N: the $1,736 Part A deductible per benefit period, $434 a day for hospital days 61–90, $868 a day for days 91–150, 365 extra hospital days after Medicare runs out, $217 a day for skilled nursing days 21–100, hospice coinsurance, blood, and foreign travel emergency at 80%. Both also leave you paying the 2026 Part B deductible of $283, up from $257 — the row that used to belong to Plans C and F, which you cannot buy at all if you were new to Medicare on or after January 1, 2020. The difference is three items: Plan N charges up to $20 for some office visits, up to $50 for an ER visit that does not end in admission, and does not pay Part B excess charges, all three of which Plan G covers. That makes the decision arithmetic rather than ideology: annual premium difference divided by $20 equals the number of office visits at which Plan N stops being cheaper. A $20-a-month gap breaks even at 12 visits a year; $30 a month at 18; $10 a month at only 6. On excess charges, Medicare’s own limiting charge caps a non-participating provider at 15% above the approved amount, and Medicare.gov says most providers accept assignment — so the honest move is to look up your actual cardiologist and primary care doctor on Care Compare rather than argue the abstraction. Plus what high-deductible Plan G’s $2,950 deductible for 2026 buys and who it fails, why the six-month Medigap open enrollment window makes this choice hard to reverse in Utah, and where the state publishes company-by-company rates. About 220,122 of Utah’s 488,797 Medicare beneficiaries were in Original Medicare in May 2026 — the group this question is actually in front of.
Read →
Aging Alone in Utah (2026): Who Decides for You, Who Provides the Care, and What It Costs to Buy
Most long-term care plans quietly assume a person who is not in the plan — a spouse, a daughter, a neighbor across the street. More than 77,000 older Utahns do not have one: about 20% of the state’s 65-and-older population lives alone, roughly 51,000 women and 26,000 men, out of 381,797 residents 65 or older in the 2020 Census DHC file. The gap has three parts and all three are fixable. First, who is legally allowed to decide. If you never sign an advance health care directive, Utah Code 75-2a-108 picks for you, in a fixed order: spouse (unless divorced or legally separated), then a single class made up of a child, parent, sibling, grandchild or grandparent, each of whom must be over 18, have decision-making capacity, be reasonably available, and not have been disqualified. A friend can serve — but only if no family is reasonably available, and only if that person clears four statutory tests, including having “exhibited special care and concern” for you and knowing your personal values; a hospital with reasonable doubt may demand a sworn statement or ask a court. When nobody qualifies, what is left is a guardianship or conservatorship, where Utah courts appoint an attorney for the adult, prefer a limited guardianship, require conservators to pass a test, file an inventory within 90 days, and account annually. Second, who physically shows up. The Administration for Community Living reports that about 80% of care at home is unpaid family and friend labor, averaging 20 hours a week, 58% of it hands-on personal care — the exact subsidy a solo ager does not have, layered on top of the familiar 70% lifetime odds of needing care. Third, what replacing it costs: Utah medians of about $4,685 a month for assisted living, $6,864 for homemaker care, $7,245 for a home health aide, $8,365 for a semi-private nursing home room and $10,646 for a private room — roughly $86,944 a year to hire what a daughter would have done free. Plus why Medicare never fills this gap, what Utah’s rural county concentrations mean for supply, and a seven-step plan.
Read →
Leaving Money to a Disabled Adult Child in Utah: Special Needs Trusts and ABLE Accounts (2026)
The will says “one-third to each,” and nobody ever asked what one-third does to the child who receives SSI. The month after it lands it is a countable resource, and SSI stops — the 2026 federal benefit rate is $994 a month for an individual and $1,491 for a couple, but the resource limits underneath it have not moved in decades: $2,000 and $3,000. In Utah the Medicaid that came with the SSI usually stops too. The fix is ownership, not amount. A third-party special needs trust funded with your money is the tool most Utah parents actually need, and it works for a narrow, precise reason: SSA counts trust principal only when the beneficiary “has legal authority to revoke or terminate the trust” or “can direct the use of the trust principal for their support and maintenance.” Draft neither in, and federal law requires no Medicaid payback — you name who inherits the remainder, at any age. Money that is already the child’s is a different animal: a 42 U.S.C. 1396p(d)(4)(A) trust, which Utah DHHS Medicaid Policy 512-2.3 (effective February 1, 2025) requires be irrevocable, established before age 65 and funded before age 65, with additions after 65 treated as a transfer for less than fair market value, reported within 10 days, never convertible into a pooled trust — or a pooled trust run by a nonprofit, allowed at any age, which may retain up to 50% of what remains. Both repay the State at death. Then the trap written straight into Utah’s manual: put your money into your child’s first-party trust and the State “treat[s] assets placed in a Special Needs trust from a third party as gifted to the disabled individual,” subject to Medicaid repayment — dollars that would have passed to your grandchildren clean. And the genuinely new thing this year: the ABLE Age Adjustment Act took effect January 1, 2026, raising the disability-onset age from 26 to 46 and making roughly six million more people eligible, with a $20,000 aggregate contribution limit for 2026 under Rev. Proc. 2025-32, the first $100,000 invisible to SSI, SSI suspended rather than terminated above that, Medicaid continuing through the suspension, and distributions never counted as income. Plus the ABLE to Work add-on, why an IRA beneficiary form outranks your will, how the SECURE Act’s disabled eligible designated beneficiary rule buys a lifetime payout instead of ten years, and a seven-step Utah checklist.
Read →
Using the Life Insurance You Already Own to Pay for Long-Term Care in Utah (2026)
A policy from 1998 surfaces in a filing cabinet just as the assisted living deposit comes due, and the question is whether it can be turned into care. Often it can — but “cash in the policy” is one sentence covering five very different transactions. An accelerated death benefit or chronic-illness rider reduces the death benefit but generally pays tax-free: under IRC §101(g), benefits are fully excluded if a physician certifies the insured is expected to die within 24 months, while for someone chronically ill but not terminally ill, reimbursement-style benefits for qualified care are generally excludable in full and per-diem benefits are excludable only up to the IRS limit — $430 a day for 2026 under Rev. Proc. 2025-32, up from $420. Set that ceiling against what Utah actually charges in the CareScout Cost of Care Survey 2025 and it clears every common setting in the state: adult day health care $140 a day, assisted living $172, an in-home caregiver at 44 hours a week $246, a semi-private nursing-home room $285, a private room $350 — or $5,475 and $10,646 a month for assisted living and a private room. A cash-value loan is the fastest money in the house and generally not taxable while the policy stays in force, but an over-loaned policy can lapse and hand you a tax bill on gain you never held. A §1035 exchange can move an unwanted death benefit into a hybrid life/LTC or qualified LTC contract with no gain recognized and basis carried over — IRS Notice 2011-68 confirms the Pension Protection Act opened this for exchanges after December 31, 2009 — though insurability, not tax law, is what usually stops it. Selling the policy is legal here and closely governed by the Utah Life Settlements Act: licensed provider and producer, $250,000 of financial responsibility, a signed disclosure that must list the accelerated death benefit and loan alternatives first, escrowed proceeds paid within three business days, a producer who “represents only the owner” and owes a fiduciary duty, an unconditional 15-day right to rescind, and a two-year waiting rule with nine specific exceptions. Plus what each route does to Medicaid eligibility, why surrender is almost always last, and the five checks to run — starting with the NAIC Policy Locator, which has matched more than $13 billion in benefits since 2016 — before you touch the contract.
Read →
Paying Off Your Mortgage Before Retirement in Utah (2026)
Everyone tells you to retire the mortgage before you retire. Nobody tells you what the money to do it costs. The honest version of the question is not whether debt is bad — it is which account the payoff comes out of, because the same $180,000 balance retired from three different places produces three completely different bills. From taxable savings or a Roth, nothing lands on your tax return at all. From a traditional IRA or 401(k), every dollar is ordinary income, taxed federally and again by Utah at the flat 4.45% rate set by S.B. 60 for tax years beginning on or after January 1, 2026 — which means you cannot pay off a $180,000 mortgage with a $180,000 withdrawal. At a 24% federal marginal rate plus Utah’s 4.45%, you would need to pull roughly $251,572 to net $180,000, about $71,572 of tax to avoid $76,464 of interest spread over twelve years. Then Medicare reads that return two years later: the grossed-up withdrawal lands the couple in the $342,001–$410,000 IRMAA bracket, adding about $9,240 of Part B and Part D surcharges for the year, and the brackets are cliffs — one dollar above $274,000 joint costs a couple roughly $3,473, with no phase-in and no proration. Meanwhile the tax break people think they are protecting is usually worth nothing: mortgage interest is an itemized deduction under IRS Publication 936, and a Utah couple both 65 or older starts 2026 with a $35,500 standard deduction against about $10,955 of annual interest. Plus the five middle paths most households skip — splitting the withdrawal across two tax years, paying down and recasting, using RMD money that was leaving anyway — the five cases where paying it off is still clearly right, what property tax and insurance keep costing after the loan is gone against Utah’s $455,000 median home value, and the September 1 circuit-breaker deadline worth up to $1,412.
Read →
Before You Sign an Annuity in Utah: Surrender Charges, Fees & the Rules on Your Side (2026)
An annuity is a long contract with a short escape hatch, and Utah law is more specific about both than most buyers realize. Every new life insurance policy and annuity issued in or delivered in Utah must carry an examination period of at least 10 days — 30 days if it replaces an existing policy — printed prominently on the cover page, and the Utah Insurance Department is blunt about what happens after: “the insurance company is under no obligation to return the full premium after the examination period expires.” Surrender charges have hard stops here too. The department’s Individual Annuity Content Standards require that charges equal zero at the later of attained age 70 or the tenth contract anniversary, and that for seniors age 60 and over they be “limited to 10 years and … generally limited to a maximum initial charge of 10%.” The data page must spell out guaranteed rates, surrender and partial-withdrawal charges, any market value adjustment, and — on indexed contracts — the minimum participation rate, minimum cap, and maximum spread; withdrawals on rolling-charge contracts must come out smallest-penalty-first. On the sales side, Utah Admin. Code R590-230-4, amended effective December 8, 2023, requires a producer to act in your best interest without placing their own or the insurer’s financial interest first, and to hand you a written disclosure naming which products they’re licensed to sell, whether they represent one insurer or several, and how they’re paid — though the rule says plainly it does not create a fiduciary relationship. On a replacement, the producer must weigh a new surrender period, lost benefits, and whether you’ve exchanged an annuity in the preceding 60 months. Plus the SEC’s numbers on what a contract costs to own (a 7%-declining surrender schedule, an M&E charge near 1.25% a year, administrative fees around 0.15% or $25–$50, and a bonus-credit example where a 4% bonus at 1.75% in fees ends year ten behind a no-bonus contract at 1.25% — $229,780 versus $231,360), the IRS 10% additional tax on distributions before 59½, why no government agency guarantees any of it, the Utah guaranty association caps of $250,000 for annuities, $200,000 for net cash surrender value and $500,000 for death benefits, and nine questions to ask before you sign.
Read →
FEHB and Medicare Part B: Utah Federal Retirees (2026)
Utah has roughly 36,900 federal government jobs — Hill Air Force Base, the IRS campus in Ogden, the VA, the Forest Service, the Postal Service — and every one of those careers ends at the same fork: take Medicare Part B on top of FEHB, or don't. Part B is voluntary for federal annuitants and OPM never requires it. What OPM does say is what happens if you change your mind: “If you wait 12 months or more, after first becoming eligible, your Part B premium will go up 10 percent for each 12 months that you could have had Part B but didn't take it.” The trap is the timing. While you're an active employee past 65, FEHB is coverage based on current employment and Medicare waits. The day you retire it becomes retiree coverage — and Medicare.gov is blunt that the 8-month Special Enrollment Period “starts when you stop working (or lose insurance), even if you choose COBRA or other coverage that's not Medicare.” Miss it and you're left with the General Enrollment Period, January 1–March 31, and a permanent surcharge: 20% takes the 2026 premium from $202.90 to $243.50, and ten years late doubles it to $405.80. Drug coverage runs the other way — OPM states flatly that as long as you have FEHB you owe no Part D late enrollment penalty. Postal retirees have their own rulebook: under the Postal Service Reform Act of 2022, certain Medicare-eligible PSHB annuitants must take Part B, with exceptions for those who retired on or before January 1, 2025, were 64 or older on that date, live abroad, or hold qualifying VA or Indian Health Service benefits. CMS data for May 2026 shows 38,968 Utahns — 8.0% of the state's 488,797 beneficiaries — holding Part A without Part B, running from 10.1% in Tooele, 9.1% in Salt Lake, 8.8% in Davis and 8.6% in Weber down to 5.2% in Washington County. Plus the 2026 costs ($202.90 premium, $283 deductible, IRMAA from $109,000), the four ways FEHB and Medicare can be combined, why cancelling FEHB as an annuitant can never be undone, and a nine-step checklist before you decide.
Read →
Medicare Fraud and Elder Scams in Utah: A 2026 Guide
The people who target retirees are not guessing. They know the enrollment calendar, they know what a Medicare Number is worth on a billing form, and they know a call about your health coverage in late October sounds like housekeeping rather than a pitch. The FBI's Internet Crime Complaint Center puts numbers on it: in 2025, Utah complainants age 60 and over filed 2,341 complaints and reported $65,946,070 in losses — roughly 24% of the state's complaints but about 34% of the $195.4 million Utahns of every age lost. Nationally the 60-and-over totals reached 201,266 complaints and $7.748 billion, up 59% in a single year, with an average loss above $38,500 and 12,444 people losing more than $100,000 apiece. Investment fraud alone took $3.5 billion from that age group, and government impersonation roughly doubled year over year, from 4,521 complaints to 8,628. Almost every one of these schemes asks for the same three things — your Medicare Number, remote access to a device, or money moved in a way that cannot be reversed. Here is the table of what Medicare and Social Security will never do (Medicare will never call to sell you anything or visit your home; SSA will never suspend your number or ask for gift cards), how the federal marketing rules give you something concrete to check on any enrollment call — recorded calls under 42 CFR 422.2274, a Scope of Appointment 48 hours before an in-home visit, and an agent who states outright that they do not offer every plan — how to catch medical identity theft on a Medicare Summary Notice, what to do in the first 24 hours, and every free Utah number worth having on the refrigerator.
Read →
Beneficiary Designations in Utah: The Paperwork That Overrides Your Will (2026)
Most Utah families pay for a will and then never look again at the one-page forms that actually move the biggest assets they own. Life insurance, annuities, IRAs, 401(k)s, HSAs, and payable-on-death bank accounts are nonprobate transfers — they pay the name on the beneficiary form the company has on file, and a will generally cannot reach them. Utah Code 75-2-804 does revoke a revocable designation naming a former spouse after a divorce or annulment, and the statute is explicit that no other change of circumstances effects a revocation — not estrangement, not remarriage, not a sentence in your will. But the state rule stops at the federal line: in Egelhoff v. Egelhoff, 532 U.S. 141 (2001), the Supreme Court held ERISA preempts state revocation-on-divorce statutes for employer plans, so a 401(k), pension, or group life policy pays whoever is on the plan’s form. Federal law also makes a married participant’s spouse the default beneficiary of an ERISA plan unless the spouse signs a written, witnessed consent — a protection that does not follow the money into an IRA. The scale of the paperwork problem is measurable: the NAIC Life Insurance Policy Locator has matched more than 611,000 policies worth $13.18 billion through August 31, 2025, and Utah’s treasurer returned a record $43.4 million in unclaimed property in FY 2025, with unpaid insurance benefits among the sources. CDC data puts Utah’s divorce rate at 3.1 per 1,000 in 2023. Plus the five costliest mistakes — no contingent beneficiary, “my estate” by default, minors named directly, trusts drafted without coordination, and lump sums to a beneficiary on means-tested benefits — and a seven-step audit you can finish in an afternoon.
Read →
Medicare Part D Late Enrollment Penalty: A Utah Guide (2026)
Almost nobody skips Medicare's drug coverage on purpose — they skip it because they take no pills, or because a letter about “creditable coverage” looked like junk mail. The bill arrives years later, every month, for life. In 2026 the Part D late enrollment penalty is 1% of $38.99 (the national base beneficiary premium CMS set on July 28, 2025) for every full month you went without Part D and without creditable drug coverage, rounded to the nearest $0.10 and bolted onto your premium. It starts once a gap runs 63 days or more after your Initial Enrollment Period ends — and the test never closes, so dropping a drug plan at 71 counts the same as never enrolling. A two-year gap costs $9.40 a month; five years, $23.40; ten years, $46.80 — more than the base premium itself, buying nothing. The one document that protects you is the notice of creditable coverage your employer, union, retiree plan, or COBRA administrator must send before October 15 every year, right before the October 15–December 7 enrollment window. CMS data for May 2026 shows 96,972 of Utah's 488,797 Medicare beneficiaries — 19.8% — with no Medicare drug coverage at all, running from 15.3% in Cache County to 25.6% in Tooele, 25.3% in Weber, and 24.0% in Davis. Most of those households hold creditable coverage through TRICARE For Life, the VA, FEHB, or a job. Some do not know which group they are in. Plus what counts as creditable, how the 60-day reconsideration appeal works, and how the Part B penalty (10% per full 12 months on $202.90) compares.
Read →
The Fall That Starts Long-Term Care: Utah's Numbers and What Medicare Actually Pays (2026)
For most families long-term care does not begin with a diagnosis — it begins with a step, a hospital bed, and a discharge planner asking where mom goes next. CDC counts more than 14 million adults 65 and older, about 1 in 4, falling every year, roughly 3 million emergency department visits and 1 million hospitalizations, including nearly 319,000 for hip fractures — and falling once doubles the odds of falling again. Utah is above the national average: 331 unintentional fall deaths among adults 65+ in 2023, a crude rate of 79.4 per 100,000 versus 69.9 nationally (NCHS Data Brief No. 532, June 2025), and the national age-adjusted rate climbed 21% from 2018 to 2024. The risk is not flat across retirement — the 2023 rate runs 19.2 per 100,000 at ages 65–74, 74.7 at 75–84, and 339.5 at 85 and older. Here is exactly what Medicare pays after a fall (a 3-day inpatient stay first — observation hours do not count — then $0 a day for days 1–20, $217 a day for days 21–100, and all costs after day 100 in 2026), where custodial care leaves Medicare behind, and what the next dollar costs in Utah at roughly $4,685 a month for assisted living and $10,646 for a private nursing home room.
Read →
Medicare and Medicaid Together in Utah: The 2026 D-SNP Guide
Having Medicare and Medicaid at once takes most of the cost out of the Medicare system and adds most of the confusion. Utah has 12 Dual Eligible Special Needs Plans in 2026 — 21,749 enrollees across eight contracts from UnitedHealthcare, Molina, Humana, Select Health, Aetna, and Devoted (CMS SNP Comprehensive Report, July 2026) — and CMS classifies every single one of them as coordination-only. None is a FIDE SNP, a HIDE SNP, or an applicable integrated plan, and CMS’s contract-year-2026 file marks all 12 “Eligible for Integrated Care SEP: No.” That has a hard consequence most people learn the expensive way: the monthly integrated care SEP does not exist in Utah, and since January 1, 2025 the monthly dual/LIS SEP can only move you to Original Medicare plus a standalone Part D plan — never between Medicare Advantage plans. So a Utah dual generally switches D-SNPs only from October 15 to December 7, or January 1 to March 31. Plus what each Medicaid category actually pays in 2026 (QMB covers the $202.90 Part B premium, the $1,736 Part A deductible, and the $217/day skilled nursing coinsurance — and QMB enrollees cannot legally be billed for Medicare cost sharing), the 2026 Extra Help drug copays, and why Utah’s $2,000 full-Medicaid asset limit is a fifth of the $9,950 limit that applies to the Medicare Savings Programs.
Read →
Check Your Social Security Earnings Record Before You Retire (Utah, 2026)
Most retirement plans are anchored to a number nobody ever verifies — the Social Security estimate on the statement. It is generated from a lifetime earnings record that employers, the IRS, and SSA's matching software all helped build, and it comes with a deadline: ordinarily you cannot correct a year's earnings after 3 years, 3 months and 15 days from the end of that tax year, though SSA lists four real exceptions that stay open if you kept the paperwork. The scale of the problem is published: SSA posts roughly 260 million wage items a year where the name and SSN match, cannot match about 3 percent of them, and in recent years has added about 8 million new wage items a year to the Earnings Suspense File while pulling only about 1 million back out — a file that had accumulated over 381 million items for tax years 1937–2019 as of October 2021 (SSA OIG, June 2023). Wages sitting there count toward nobody's benefit. Here is how the 35-highest-years formula turns one bad line into a permanent monthly deduction, the seven-step way to read and fix the record, why self-employed Utahns carry extra risk, and what Utah's December 2025 numbers look like: 373,883 retired workers collecting about $810.7 million a month, roughly $2,168 each.
Read →
Do You Need a Living Trust in Utah? A 2026 Probate Guide
Someone at a seminar said you need a living trust and quoted a few thousand dollars. Sometimes that is right; often it is an expensive answer to a problem two beneficiary forms and one recorded deed already solve. We pulled the Utah judiciary's own filing data: Utah district courts opened 3,329 estate probate cases in FY2026, up roughly 80% since FY2010, with Salt Lake County alone accounting for 1,207 and Washington County 250. Here is what probate actually does in Utah — informal, filed no sooner than 120 hours after death and generally within three years, at a $375 petition fee — which assets already skip it, and why the $100,000 small estate affidavit under Utah Code 75-3-1201 handles bank accounts and up to four vehicles but never real estate, which is why the house drives the whole decision. Plus the six steps to a valid Utah transfer-on-death deed under the Uniform Real Property Transfer on Death Act (75-6-401 et seq.), the three limits nobody mentions, when a trust genuinely earns its cost, the unfunded-trust failure mode — and the hard part: Utah defines a Medicaid "recovery estate" to expressly include joint tenancy, life estates, and living trusts, and voids any trust provision denying recovery, so none of these tools is an asset-protection strategy here.
Read →
Do You Need an Inflation Rider on Long-Term Care Insurance? A Utah Guide (2026)
The least exciting line on a long-term care illustration usually decides whether the policy works. A couple shopping coverage in Provo at 58 is buying protection against a bill that arrives in the 2040s — and Utah's cost growth is real: in the CareScout (Genworth) Cost of Care Survey 2024, Utah assisted living rose 13% in a single year, a semi-private nursing-home room rose 10%, and a home health aide rose 9%. Nationally the pace eased in the 2025 survey, with most settings up 1% to 5% (assisted living +5% to $6,200/month; semi-private nursing home +2% to $315/day; in-home caregiving +3% to $35/hour). Here is what each inflation option actually does to a $200/day benefit: no rider leaves it at $200 forever, 3% simple reaches about $320/day in 20 years, 3% compound about $361, and 5% compound about $531 — with the gap widening to $380 vs. $485 vs. $864 by year 30. Plus why the un-indexed benefit already falls short of Utah's $275/day semi-private rate today, which option tends to fit buyers in their 50s, 60s, and 70s, what rural Utah families should watch for, the alternatives to a steeper rider, and what happens to your rider if the carrier requests a rate increase.
Read →
Social Security's 2034 Shortfall: What It Actually Means for a Utah Retirement
The 2026 Trustees Report kept the headline date at 2034 — and quietly made the long-run gap worse. Here is what the report actually says: combined trust fund reserves depleted in 2034 with 83% of scheduled benefits payable, and the retirement fund on its own (OASI) depleted in the fourth quarter of 2032 with 78% payable. That is a shortfall, not a shutdown, and the two dates are both correct because they describe two different legal trust funds. What a 17% reduction does to a Utah check: the state's average retired-worker benefit works out to about $2,168/month (computed from SSA's December 2025 state tables), so roughly $369 a month or $4,423 a year — closer to $8,800 for a two-earner couple. Utah is the youngest state in the country, with only 13.8% of all residents drawing a benefit, yet 87.0% of Utahns 65 or older receive one, and Social Security pays about $980 million a month into Utah households. Plus the Trustees' own price tag on a fix (payroll tax 12.40% → 16.65% if done in 2026, versus 17.30% if deferred to 2034), why claiming early out of fear usually backfires, and the four parts of a retirement plan you actually control.
Read →
How to Choose a Nursing Home in Utah (2026): Star Ratings, Staffing & What to Ask on the Tour
Almost nobody shops for a nursing home calmly — it happens after a fall or a stroke, from a discharge planner's list, with a decision due Friday. Utah has 98 certified nursing facilities and has had roughly 98 every year since 2016 (KFF analysis of Nursing Home Compare), so along the Wasatch Front you may have a real choice and in San Juan or Emery County you may have one. The CMS overall star is a composite you can take apart: it starts as the health-inspection rating, adds a star when staffing rates 4 or 5 and beats inspections, subtracts one when staffing rates 1, and moves again on quality measures — which means a home with a shaky inspection history can still show 4 stars. Two methodology changes matter now: since the July 2025 refresh CMS uses the two most recent standard surveys instead of three, and since January 2026 the long-stay antipsychotic measure is a respecified claims-based version scored in deciles. Plus what a Utah nursing home actually costs ($275/day semi-private, $350/day private, CareScout 2024), the staffing and turnover numbers that predict more than the stars do, the eight questions to ask on the tour — including the Medicaid spend-down question that prevents a forced move later — and how Utah's Long-Term Care Ombudsman works if something goes wrong.
Read →
Are Long-Term Care Costs Tax Deductible in Utah? (2026)
Some of it, some years — and almost none of the tax break comes from Utah. A tax-qualified long-term care premium counts as medical care only up to an age-based cap that runs $500 at 40 or under, $1,860 above 50, $4,960 above 60, and $6,200 above 70 per insured person for 2026 (IRS Rev. Proc. 2025-32). Care itself counts too — nursing home in full when the stay is primarily for medical care, and the personal-care share of assisted living when a practitioner has certified the resident chronically ill under a plan of care. Then the 7.5%-of-AGI floor and a $35,500 standard deduction for a couple in their seventies wipe out an ordinary year and leave a heavy care year standing. Utah has no medical deduction at all: it has a flat 4.45% rate for 2026 under S.B. 60 and a taxpayer tax credit worth 6% of your federal deduction, so deducting more federally quietly pays twice. Plus the Health Benefit Plan Credit that covers Part B, C, and D but expressly excludes long-term care and Medigap, and the new $2,600 penalty-free 401(k) withdrawal for premiums that IRAs cannot use.
Read →
Your Long-Term Care Premium Just Went Up: What Utah Policyholders Can Do (2026)
A rate-increase letter on a twenty-year-old long-term care policy reads like an ultimatum — pay 60% more or lose everything you put in. It is not one. Utah's Long-Term Care Insurance Rule R590-148 opens a 120-day window with four doors in it, and the state publishes the exact threshold that unlocks them: a cumulative increase over your INITIAL annual premium of 90% at issue ages 55–59, 70% at 60, 50% at 65, 40% at 70, 30% at 75, 20% at 80. Meet it and the insurer must convert the policy to paid-up coverage worth 100% of every premium you ever paid — never less than 30 times your daily nursing-home benefit — and a lapse inside those 120 days counts as electing it. Before the increase even takes effect the company must also offer to cut benefits with no additional underwriting so your payment does not rise at all. Plus the 85-cents-on-the-dollar loss-ratio rule the insurer had to satisfy to raise your rate, the rate-spiral remedy, and the 2026 IRS deduction caps that may have moved with your premium.
Read →
Can You Pay a Family Member to Provide Care in Utah? (2026)
Paying an adult child to care for a parent is legal, common, and often the best use of a Utah family's money — but the way most families do it, a monthly transfer with no paperwork, is the version that fails later. Utah Medicaid policy 575 is blunt: money paid to someone for services already provided is treated as a transfer of assets unless a signed written contract describing the services, the amount, and the payment schedule was in place BEFORE the care began — and prepaying more than one month's worth is a transfer even under a contract. That matters for 60 months. Meanwhile Utah's Aging Waiver rate sheet effective July 1, 2026 pays a participant-employed personal attendant $29.76 an hour at the maximum allowable rate versus $37.20 through an agency, the VA stipend keys to the OPM GS-4 step 1 locality rate, and the IRS makes your parent a household employer at $3,000 in cash wages. Here are all three routes, what each pays, and the one document that separates a wage from a gift.
Read →
Medicare Before 65 in Utah (2026): SSDI, the 24-Month Wait & the Medigap Gap
In April 2026 CMS counted 40,601 Utahns on Medicare who qualified through disability rather than age — 8.3% of the state's 487,360 beneficiaries, and 71% of them between 45 and 64. Almost every federal rule treats them exactly like a 70-year-old: same Part A, same $202.90 Part B premium, same $283 deductible. One rule does not. Federal law does not require insurers to sell Medigap policies to people under 65, and Utah's open-enrollment protection at R590-146-11 is expressly keyed to the six months beginning the first month a person is both 65 or older and enrolled in Part B — so the Utah Insurance Department lists being "under the age of 65 and disabled" among the reasons you might not be able to buy one. Here is the real 29-month clock from disability onset to a Medicare card, the ALS and ESRD exceptions, why premium-free Part A survives 93 months past a trial work period, the counties where this is most common (Carbon 13.3% vs. Summit 2.8%), and the six-month window that opens — once — on the 65th birthday.
Read →
How to File a Long-Term Care Insurance Claim in Utah (2026): Benefit Triggers, Elimination Periods & Appeals
Owning a long-term care policy and being paid by one are two different things. Utah's Long-Term Care Insurance Rule (R590-148) sets floors most families never hear about: a policy may not require a deficiency in more than three activities of daily living, cognitive impairment alone must be an alternative path to benefits, and "deficiency" may not be defined more strictly than needing hands-on help — or, if the cause is cognitive, needing supervision or verbal cuing. On a tax-qualified contract a licensed practitioner certifies an expected 90 days of inability, and once the insured is in claim status that certification may not be rescinded or re-done until the 90 days run out. Then the elimination period: at Utah's median home health aide cost of $7,245/month (CareScout), a 90-day wait is roughly $21,400 out of pocket before a dollar arrives. Plus the 2026 IRS $430/day tax-free cap (Rev. Proc. 2025-32), the four-step appeal path through the Utah Insurance Department, and the five-month window to reinstate a policy that lapsed while a parent was already declining.
Read →
Medicare When You Travel: Snowbirds & Utah Retirees (2026)
In April 2026 CMS counted 487,360 Medicare beneficiaries in Utah, and 268,071 of them — 55.0%, above the 51.2% national share — were in Medicare Advantage or another health plan built around a county-shaped service area. Federal rule: the plan must disenroll you after more than six consecutive months outside that area (42 CFR 422.74), unless it offers an optional visitor/traveler benefit that stretches the limit to 12 months — and only within the United States. Original Medicare has no absence rule at all and travels to any U.S. provider that accepts it. Outside the country, Medicare pays almost nothing: three narrow exceptions, a cruise-ship rule that ends six hours from a U.S. port, and no drug coverage anywhere. Medigap Plans C, D, F, G, M, and N pay 80% after a $250 annual deductible for care starting in the first 60 days of a trip, capped at $50,000 for life. Plus why dropping Part B abroad usually costs more than keeping it.
Read →
Claimed Social Security Too Early? Three Ways to Undo It (Utah, 2026)
Filing at 62 costs 30% of your full benefit for life — and 35% of a spouse’s — but Social Security keeps three legitimate undo buttons, each with its own deadline. You can withdraw the application entirely within 12 months of approval (once per lifetime, Form SSA-521) if you can repay every dollar you and your family received, including withheld Medicare premiums. You can suspend payments at full retirement age and earn 2/3 of 1% a month — about 8% a year — until they restart automatically at 70, though family benefits on your record stop and CMS starts billing you for Part B. And the one almost nobody mentions: benefits withheld under the 2026 earnings limits ($24,480 under FRA, $65,160 in your FRA year) get credited back when you reach full retirement age. Here’s which door is still open, and what each one costs.
Read →
Power of Attorney & Advance Directives in Utah (2026)
Utah replaced its advance-directive law on January 1, 2026 with the Uniform Health Care Decisions Act (Title 75A, Chapter 9) — and the old “75-2a” citation is retired. Sign nothing and Utah picks for you from a 10-class default surrogate ladder where adult children and parents share one class and ties are settled by majority vote. The two documents sign differently (health care POA: one witness, no notary; financial POA: notarized), and 8 financial powers — including changing a beneficiary designation and waiving a joint and survivor annuity benefit — exist only if your document expressly grants them. Then there’s the part families discover at the worst moment: Social Security does not accept a power of attorney at all, and Medicare and the IRS each want their own form.
Read →
What Long-Term Care Insurance Costs at 55, 60, and 65 (2026) — and Why Waiting Gets Expensive
A couple both age 55 pays about $5,010 a year combined for $165,000 in long-term care benefits each, growing 3% yearly; wait until 65 and the same design runs about $7,030 (AALTCI 2026 Price Index) — if you still qualify, because about 30% of applicants in their 60s are declined and roughly half after 70. The buy-early math is stronger than the sticker prices suggest: the 55-year-old couple pays only ~6% more in total premiums by age 85 but walks into their 80s with a benefit pool worth about $400,500 per person versus $298,500. Plus the 56% price spread between insurers for identical coverage, why a single woman at 60 pays $4,550 versus $2,610 for a man, and what the underwriting clock means for Utah families weighing when — and whether — to buy.
Read →
Selling Your Home in Retirement: A Utah Guide (2026)
Utah house prices rose 124% in the ten years through 2026 Q1 and 4.2× over thirty (FHFA), so a long-held Utah home can blow past the $250,000 capital gains exclusion without being a mansion. Married couples get $500,000 and usually owe nothing — but a widowed seller keeps that $500,000 only if the house sells within two years of a spouse's death, and Utah isn't a community property state, so the basis step-up generally covers only the decedent's half. On a $450,000 gain the difference runs about $47,600 once you add federal capital gains tax, the 3.8% net investment income tax, Utah's flat 4.5%, and the Medicare surcharge that lands two years later — which Social Security won't waive, because a home sale isn't a qualifying life-changing event. Here's the whole sequence, plus the care-facility exception and the Medicaid trap.
Read →
Adult Day Care & Respite Care in Utah (2026): What a Caregiver Break Costs — and Who Helps Pay
Nearly 600,000 Utahns provide unpaid care to a family member — about 490 million hours a year, worth roughly $10 billion (AARP, 2026). The break that keeps them going, adult day health care, runs a median ~$875/week (~$45,500/year) in Utah — far above the $26,000 national median, yet still the least expensive paid care setting in the state (CareScout 2024). Medicare mostly won't pay for it — the exception is short-term inpatient respite under hospice at 5% coinsurance — but Utah Medicaid's Aging and New Choices waivers, the Older Americans Act caregiver program (respite for 604,000+ caregivers nationally, 74% say it let them keep caregiving longer), VA respite benefits, and most long-term care policies do. Here's each payer, what it covers, and how to line them up before burnout makes the decision for you.
Read →
Pension Lump Sum vs. Monthly Payments: A Utah Guide (2026)
A buyout offer is really a question about who carries the risk that you live a long time. Monthly payments leave longevity and investment risk with the plan; a lump sum moves both to you — and ends your PBGC protection, which for 2026 plan terminations guarantees up to $7,789.77 a month at age 65. A payout paid to you is ordinary income with mandatory 20% federal withholding unless it goes by direct rollover (IRS), taking it in cash before 59½ can add a 10% tax (with an age-55 separation exception that doesn't apply to IRAs), and a six-figure taxable year can raise your Medicare premiums two years later. Utah public employees are a separate case: PBGC generally doesn't insure government plans, and Utah Retirement Systems covers about 252,345 members across 493 employers.
Read →
Continuing Care Retirement Communities (CCRCs) in Utah (2026): Entrance Fees, Contract Types & What to Check Before You Sign
A CCRC puts independent living, assisted living, and skilled nursing on one campus — in exchange for an entrance fee that averages about $402,000 nationally (range ~$40,000 to $2M+) plus a monthly fee that averaged $3,555 and typically rises ~2% a year (NIC data via AARP). Utah licenses CCRC providers through the Utah Insurance Department under the Continuing Care Provider Act (Utah Code 31A-44), and providers must file a disclosure statement — but the department is barred from regulating quality of care, so diligence is a two-track job. Here are the three contract types (A, B, C) and who carries the care-cost risk under each, the four entrance-fee refund structures GAO found, why GAO warns residents can lose an entrance fee if a community fails, and the exact questions to ask before you sign.
Read →
Can You Use an HSA for Medicare and Long-Term Care in Retirement? (Utah 2026 Guide)
After 65, your HSA can pay Medicare Part B, C, and D premiums tax-free — but not Medigap — and long-term care insurance premiums up to $4,960 a year at ages 61–70 (2026 IRS limits). Plus the 6-month rule for stopping contributions that catches Utahns who work past 65.
Read →
VA Benefits & Medicare in Utah (2026): Do You Need Part B?
"Veterans' benefits" is three different programs with three different answers. VA health care does not require Medicare Part B — but VA itself tells you to take it, because VA only pays at a VA (or VA-authorized) location. TRICARE For Life is the opposite: TRICARE.mil defines it as "Medicare-wraparound coverage if you're TRICARE-eligible and have Medicare Part A and Part B," so dropping Part B ends the wraparound. CHAMPVA requires Part A and Part B once you're Medicare-eligible. VA drug coverage is creditable for Part D, but it is no shield against the Part B penalty — 10% for every full 12 months you skipped, for life, which on 2026's $202.90 premium is $243.50 a month after just two years. Here's the sorting for the 53,533 Utah veterans age 65 and older, with the federal language behind every line.
Read →
Moving to Utah in Retirement (2026): Medicare & Taxes
Part A, Part B, IRMAA, and your Social Security check are federal — they cross the state line unchanged. Medicare Advantage and Part D plans are drawn county by county, so a move can end the plan you have and opens a Special Enrollment Period that starts a month earlier if you tell the plan first. Here's what survives a move, the 2-full-month deadline, when a move opens a Medigap door, how Utah taxes retirement income, and why snowbirding doesn't change your domicile.
Read →
How to Appeal a Medicare Denial in Utah (2026): 5 Levels
Medicare Advantage plans overturned 95% of appealed skilled nursing denials — but only 18% of those denials were ever appealed. Here are Utah's five appeal levels, the 2026 filing deadlines and decision timeframes for Original Medicare, Part C, and Part D, the calendar-year 2026 amount-in-controversy thresholds, and where to get free help.
Read →
Early Retirement in Utah: Healthcare Planning for Ages 60–64 Before Medicare (2026)
Retiring at 60, 62, or 64 in Utah? The ACA Marketplace with subsidies is your path to healthcare. Nearly 90% of Utah enrollees qualify for premium credits averaging $499/month. Here is how to manage income to keep subsidies, and why COBRA alone won't bridge the gap to Medicare.
Read →
Fixed Annuities & Lifetime Income: Lock in Guaranteed Payouts in Utah (2026)
How fixed annuities convert savings into guaranteed lifetime income. August 2026 rates reach 7.20%, and a deferred income annuity can double your payout by waiting 10 years. Here's how they work, what you'll earn, and whether one fits your Utah retirement plan.
Read →
Qualified Charitable Distributions (QCDs): Donate to Utah Nonprofits, Satisfy Your RMD, and Cut Taxes
A QCD lets Utah retirees age 70½+ donate directly from their IRA to 501(c)(3) charities, exclude the donation from taxable income, and count it toward their RMD. Up to $111,000 per person in 2026. How it works, tax benefits, and practical planning for Utah families.
Read →
Medigap Birthday Rule in Utah (2026): How to Switch Plans
Utah added a Medigap birthday rule in 2025, and it is narrower than the ones you've read about from California or Oregon. Under Utah Code §31A-22-620(3)(g), effective May 7, 2025, every Medicare supplement policyholder gets a 60-day window each year, starting on their birthday, to move to a different plan without medical underwriting — but only to a "comparable or lower tier" plan offered by the insurance company they already have. It will not move you to a different carrier, will not upgrade your benefits, and is not a door out of Medicare Advantage. The one broad window is still federal: the one-time 6-month Medigap Open Enrollment Period that starts the first day of the month you're 65 or older and enrolled in Part B. And Utahns under 65 still have no state-guaranteed path into Medigap — H.B. 340 in the 2026 session would have created one, and it was not enacted, leaving the 40,601 Utahns on Medicare under age 65 (CMS, April 2026) with whatever companies choose to offer. Here's every window that lets you switch without health questions, what "lower tier" means, and where to get free help — with the statute and official sources.
Read →
Tax-Efficient Withdrawal Sequencing in Utah Retirement: Maximize After-Tax Income (2026)
The order you tap your savings accounts—taxable brokerage, traditional IRA, Roth—can add $187,000 to lifetime income. Here's the 2026 Utah strategy to optimize withdrawals across tax brackets, Medicare premiums, and state taxes.
Read →
The Social Security Fairness Act Has Eliminated GPO for Utah Teachers & Public Servants (2026)
The Social Security Fairness Act ended the Government Pension Offset (GPO) for benefits payable after December 2023. Utah teachers on URS, firefighters, police, and other public employees with spousal or widow(er) benefits can no longer have those benefits reduced or eliminated by a government pension. As of July 7, 2025, Social Security distributed 3.1 million retroactive payments totaling $17 billion, averaging about $6,710 per person. Most beneficiaries began receiving their new (higher) monthly amount starting April 2025.
Read →
Utah's Medicaid Waivers: New Choices & Aging Waiver (2026)
Utah's Medicaid home and community-based waivers can pay for care at home or in an assisted living facility instead of a nursing home — but the two senior waivers together hold about 3,050 approved slots, and the eligibility rules are not the ones most families assume. This walks through the New Choices Waiver and the Waiver for Individuals Age 65 or Older: who qualifies, what each one actually pays for, the level-of-care and cost-neutrality tests, the 2026 income and asset standards, how the waiting lists work, and how the whole thing compares with paying for a Utah nursing facility out of pocket.
Read →
Medicare's 100 Days of Nursing-Home Coverage: How the SNF Benefit Really Works (Utah, 2026)
Almost every Utah family believes Medicare pays for a nursing home — and it does, for a narrow window most people misread until the bill arrives. After a qualifying 3-day inpatient hospital stay, Medicare Part A covers up to 100 days of skilled nursing care per benefit period: $0 for days 1–20, then a coinsurance of $217 per day in 2026 for days 21–100, up to $17,360 (CMS 2026 fact sheet). Two traps catch people. First, nights spent 'under observation' are billed as outpatient and do NOT count toward the 3-day rule that unlocks the benefit (Medicare.gov). Second, the moment care stops being skilled — or day 100 arrives — Medicare pays nothing, and a Utah semi-private nursing-home room runs about $100,375 a year, a private room about $127,750 (CareScout 2024). The 100 days reset only after 60 days out of a hospital and facility, and a new benefit period brings a new $1,736 Part A deductible. Here's how the benefit really works, where the long-term care gap begins, and the five ways Utah families pay for it — with official sources.
Read →
Medicare Hospice Care in Utah (2026): Coverage & Costs
Hospice is one of the most complete benefits in Medicare and one of the least understood. It's covered under Part A with no deductible: you pay up to $5 per prescription for pain and symptom drugs and 5% of the approved amount for inpatient respite care, capped at the $1,736 Part A deductible in 2026 (Medicare.gov, CMS). You keep your Medicare Advantage plan if you have one — Original Medicare pays the hospice bill either way — and Medigap covers those two copays. The "6 months or less" certification isn't a deadline: hospice runs in two 90-day periods, then unlimited 60-day periods. In FY2023, 15,166 Utahns on Medicare used hospice, averaging about 87 days each versus about 78 nationally, and only 17% were admitted primarily for cancer against 23% nationally — heart conditions (33%) and dementia and other nervous-system conditions (25%) lead here (CMS). We pulled the CMS provider file: 84 Medicare-certified hospices list a Utah address, 68 of them in Salt Lake, Washington, Utah, and Davis counties, and 16 of Utah's 29 counties have none headquartered locally. Here's what's covered, what you pay, the room-and-board trap, and what changes October 1 — with official sources.
Read →
Memory Care Costs in Utah (2026): Paying for Alzheimer's & Dementia Care
Dementia is one of the longest and most expensive kinds of care a Utah family plans for — and the one Medicare is least likely to cover. About 38,300 Utahns aged 65 and older were living with Alzheimer's as of 2020, roughly 10% of Utah adults over 65 have the disease, and it's now the 4th-leading cause of death in the state (Alzheimer's Association 2026). Memory care is usually a secure unit inside assisted living, priced above Utah's base assisted-living rate of about $4,685/month, while a private nursing-home room runs about $127,750/year (CareScout 2024). Medicare pays only for short skilled care — not the ongoing custodial supervision dementia requires. Here's what memory care really costs on the Wasatch Front, why the bills add up faster, and the five ways Utah families pay — savings, long-term care insurance, hybrid policies, annuity income, and Medicaid — with official sources.
Read →
Utah's Circuit Breaker: Property Tax Relief Worth Up to $1,412 (2026)
Property tax is one of the few big retirement expenses that keeps climbing no matter how carefully you budget — and Utah has an income-based credit that most eligible households never claim. Just 9,207 Utah households received the state-funded homeowner's credit in 2025, against roughly 198,000 households headed by someone 65 or older, and exactly five people statewide used the deferral for owners 75 and up (Utah State Tax Commission; Census ACS 2019–2023). The circuit breaker is worth up to $1,412 for claims filed in 2026 if 2025 total household income came in under $44,221 — but the two halves use different ages that most write-ups get wrong: renters qualify at 66, homeowners at 67, or at any age as an unmarried surviving spouse. Homeowners also get an additional credit equal to the tax on 20% of the home's fair market value, stacked on the 45% primary residential exemption in the Utah Constitution. The catch is the calendar: homeowners file with their county by September 1, renters with the Tax Commission by December 31. Here are the seven income tiers, the five other relief programs, county phone numbers, the good-cause extension, and the statute renumbering that took effect January 1, 2026 — with official sources.
Read →
Divorced After a Long Marriage? You May Be Owed Social Security on Your Ex's Record (Utah, 2026)
Plenty of divorced Utahns assume an ex's work record has nothing to do with their retirement — and quietly leave hundreds of dollars a month on the table. If your marriage lasted 10 years or longer, you're currently unmarried, and you're 62 or older, Social Security may pay you a divorced-spouse benefit worth up to 50% of your ex's full-retirement-age benefit (about 32.5% if you claim at 62). It does not reduce your ex's check, your ex isn't notified, and you can even claim once you've been divorced two-plus years if your ex hasn't filed yet. If your ex has passed away, a surviving divorced spouse can receive up to 100%. Here's who qualifies, how claiming age changes the amount, and the traps to avoid — with SSA sources.
Read →
Does Medicare Cover Dental, Vision & Hearing? A Utah Guide (2026)
The biggest surprise in most first Medicare conversations isn't a premium — it's learning the program pays nothing toward a cleaning, a pair of glasses, or a hearing aid. Medicare.gov is blunt: Original Medicare doesn't cover routine cleanings, fillings, extractions, dentures, or implants; it doesn't cover routine eye exams or eyeglasses (except one pair after cataract surgery with an intraocular lens); and it doesn't cover hearing aids or the exams to fit them. What it does cover is medical — glaucoma screening for high-risk beneficiaries, a yearly diabetic retinopathy exam, doctor-ordered hearing and balance exams — at 20% after the $283 Part B deductible. Most Medicare Advantage plans add something: CMS reported 97% of MA plans offered hearing and/or dental benefits and 99% offered vision in 2025, and Utah has 55 MA plans for 2026, up from 48 (CMS). Medigap adds none of it. And the need isn't evenly spread — complete tooth loss among Utahns 65+ runs from 6.6% in Morgan County to 20.8% in San Juan County (CDC PLACES). Here's where the line falls and the four ways Utah retirees fill the gap, with official sources.
Read →
Reverse Mortgages in Utah: How a HECM Works in 2026
For most Utah retirees the house is the biggest asset on the balance sheet — about 85% of Utah households headed by someone 65 or older own their home, and the median owner-occupied Utah home is valued at $455,000 (Census ACS 2019–2023). A reverse mortgage turns part of that into cash with no monthly principal-and-interest payment. The federally insured version is the HECM, available only through an FHA-approved lender, and for case numbers assigned on or after January 1, 2026 the maximum claim amount is $1,249,125, up from $1,209,750 (HUD). The costs are front-loaded: an initial FHA premium of 2.00% of the maximum claim amount — about $9,100 on a median Utah home — plus 0.50% annually for the life of the loan (HUD Mortgagee Letter 2017-12) and a lender origination fee of $6,000 or less (CFPB). And there's a trap Utah families miss: if you're in a nursing home or assisted living more than 12 consecutive months with no co-borrower at home, the loan becomes due (CFPB). Here's how it works, what it costs, and how it collides with Medicaid planning — with official sources.
Read →
How Much Does Assisted Living Cost in Utah? (2026)
Weighing assisted living for yourself or a parent in St. George or anywhere in Utah? The first question is always what it costs and who pays. Based on the CareScout (Genworth) Cost of Care Survey 2024, Utah's median assisted living cost is about $4,685/month — roughly $56,220/year — a little below the national median of about $5,900/month. Within Utah it ranges from about $3,863/month in the Logan area to about $5,300/month in the Salt Lake City area. The catch most families miss: Medicare pays $0 toward assisted living room and board or ongoing custodial care (Medicare.gov), and about 70% of people turning 65 today will need some long-term care (U.S. Administration for Community Living). Utah's Medicaid New Choices Waiver can cover the care services in a licensed assisted living facility for those who meet a nursing-facility level of care and 2026 income up to $2,982/month — but not room and board directly. Here's the real math and how families pay, with official sources.
Read →
QLACs in Utah: Turn IRA Money Into Guaranteed Lifetime Income at 85 — and Trim Your RMDs (2026)
The one retirement risk you can't diversify away is living a very long time — about 1 in 3 of today's 65-year-olds will live past 90, and 1 in 7 past 95 (SSA). A QLAC (Qualified Longevity Annuity Contract) is Congress's tool for that risk: move up to $210,000 of traditional IRA or 401(k) money into a deferred income annuity that starts paying as late as age 85, and those dollars are excluded from your required minimum distributions until income begins (IRS Notice 2025-67). SECURE 2.0 dropped the old 25%-of-balance cap, so the flat $210,000 limit is all that applies. The payoff is two-sided: lower, less-taxed RMDs in your 70s — Utah taxes IRA withdrawals at a flat 4.45% — and a guaranteed paycheck in your late 80s and 90s, right when a semi-private Utah nursing-home room runs about $100,375/year (CareScout 2024). Here's how the strategy works, who it fits, and the trade-offs — with official sources.
Read →
The Retirement Income Gap in Utah: How Much Will Social Security Really Replace? (2026)
Most Utahns plan around their Social Security check — but it was never built to cover the whole bill. On average Social Security replaces only about 40% of pre-retirement earnings (SSA), while experts estimate you'll need 70–90% of your pre-retirement income to keep your standard of living (U.S. Department of Labor). That difference is the retirement income gap. For a Utah household that earned $6,000/month, Social Security's roughly $2,400 leaves a gap of about $1,800–$3,000 a month — $21,600–$36,000 a year — to fill from savings, pensions, work, or guaranteed income. The average 2026 retired-worker check is about $2,071/month; waiting to 70 can reach $5,181 (SSA). Here's the 2026 math and five ways to close the gap — with official sources.
Read →
The Widow's Penalty in Utah: Why a Surviving Spouse Can Owe More Tax on Less Income (2026)
When one spouse dies, the survivor keeps most of the household income — the pension, the IRA withdrawals, the larger of the two Social Security checks — but the year after, they file as a single taxpayer. That cuts the 2026 standard deduction in half (from $32,200 to $16,100) and pushes income into higher brackets sooner, so the same $130,000 of taxable income costs about $5,774 more in federal tax filing single than jointly — roughly 32% more (IRS 2026 brackets). Medicare IRMAA surcharges also begin at half the income ($109,000 vs. $218,000), and Utah's Social Security tax credit phases out sooner for single filers too (Utah Code 59-10-1042). Here's how the widow's penalty works, with a Provo example and official sources.
Read →
Retiring Before 65 in Utah: Health Insurance Until Medicare
Medicare is tied to age 65, not to retirement — so stop working at 62 and about 36 months of health coverage are yours to arrange. Those are the most expensive coverage years of your life, and 2026 made them harder: the temporary rule that let higher-income households still receive a premium tax credit applied only to tax years 2021–2025, so the 400% federal poverty level cliff is back (IRS). That line is $62,600 for one person and $84,600 for a couple. Live 2026 Marketplace figures show what's at stake — a couple both 62 in Salt Lake County pays $639.00 a month for the benchmark silver plan at $84,000 of income, and the full $2,269.00 at $86,000. That's about $19,560 a year for $2,000 of extra income. Here's how to bridge the gap with COBRA, the Marketplace, or a spouse's plan — with official sources.
Read →
Medicaid's 5-Year Look-Back in Utah: Gifting, Transfer Penalties & Protecting Assets (2026)
You can spend down almost everything, look poor enough for Medicaid on paper, and still be told it won't pay for your nursing-home care for months — because of Utah's 60-month look-back. Any assets you or your spouse gave away or sold under value in the 5 years before you apply get reviewed, and disqualifying transfers create a penalty period: the amount transferred divided by Utah's penalty divisor, reported near $7,344/month in 2026 (American Council on Aging). Gifting a $220,000 home could mean roughly 30 months with no Medicaid help — painful at a Utah nursing-home cost near $100,375/year (CareScout 2024). Some transfers are exempt (to a spouse, a disabled child, certain home transfers), and the at-home spouse keeps a Community Spouse Resource Allowance of $32,532 up to $162,660 (CMS). Here's how the rules work — with official sources.
Read →
Medicare Open Enrollment in Utah: Oct 15–Dec 7, 2026 Guide
Medicare Open Enrollment runs October 15 through December 7, 2026, and whatever you choose starts January 1 (Medicare.gov). Do nothing and your plan renews — but the plan you renew into can raise its premium, move your prescription to a higher tier, or drop your doctor, which is exactly what the Annual Notice of Change mailed by September 30 is there to tell you. Utah retirees have real choice to sort through: 24 Medicare Advantage plans with drug coverage in Salt Lake and Davis counties for 2026, 21 in Utah County and 12 in Washington County, plus 10 stand-alone Part D plans statewide priced from $0.00 to $132.60 a month (CMS CY2026 Landscape file). Here's every deadline, what you can and can't change, and why Medigap isn't part of this window — with official sources.
Read →
Utah's Long-Term Care Partnership Program: Protect Your Savings from Medicaid (2026)
Most Utah families think long-term care is all-or-nothing — pay out of pocket until it's gone, or spend down to qualify for Medicaid. There's a third path Utah wrote into state law: the Long-Term Care Insurance Partnership Program. Buy a Partnership-qualified policy and for every dollar it pays toward your care, one dollar of your assets is disregarded — protected — when you apply for Utah Medicaid, and that same amount is shielded from estate recovery (Utah Medicaid Policy Manual §513). Utah became a Partnership state on October 1, 2014. With a private nursing-home room near $127,750/year (CareScout 2024) and about 70% of 65-year-olds needing care (ACL), it's a tool worth knowing. Here's how the dollar-for-dollar disregard works — with official sources.
Read →
Inherited IRA Rules in Utah: The 10-Year Rule (2026)
Inherit an IRA from a parent or friend who died after 2019? Unless you're a spouse, the old lifetime “stretch” is gone — you generally have to empty the account within 10 years (IRS). Under the IRS final regulations now in force for 2025 and later, some heirs also owe a required withdrawal every year in years 1–9, not just a year-10 sweep, if the original owner had already started RMDs. A narrow group — surviving spouses, the owner's minor child, disabled or chronically ill heirs, and anyone not more than 10 years younger — can still stretch withdrawals over their lifetime. Miss a required withdrawal and the excise tax is 25% (10% if fixed within two years), and Utah taxes traditional-IRA withdrawals at its flat 4.45% rate for 2026. Here's how the timing works — with official sources.
Read →
Nursing Home & Medicaid in Utah: How the Healthy Spouse Keeps Their Income and Savings (2026)
If one spouse needs a nursing home, does the other lose everything? In Utah, no — federal spousal-impoverishment rules protect the spouse who stays home. In 2026 the at-home (community) spouse can keep a Community Spouse Resource Allowance of $32,532 up to $162,660 in assets (CMS), plus the home and a vehicle in most cases, while the spouse needing care is limited to $2,000. There's an income floor too: the at-home spouse's monthly income is protected between $2,643.75 and $4,066.50, and part of the institutionalized spouse's income can be shifted to close a shortfall (Medicaid.gov). With a Utah nursing-home semi-private room near $100,375/year (CareScout 2024), knowing these rules matters. Here's how it works — with official sources.
Read →
Turning 65 in Utah: When to Sign Up for Medicare (2026)
Turning 65 is the one Medicare deadline you don't want to guess at. Your Initial Enrollment Period is a 7-month window — the 3 months before your birthday month, your birthday month, and the 3 months after (Medicare.gov) — and enrolling in those first 3 months is the only way coverage starts the day you turn 65. If you're not yet drawing Social Security, nothing is automatic: you must actively sign up at ssa.gov/medicare. Miss the window without a Special Enrollment Period and the Part B late penalty adds 10% per year for life — about $20.29/month for each year late against 2026's $202.90 premium (CMS). Don't forget the separate one-time 6-month Medigap window, either. Here's the full 2026 timeline with official sources.
Read →
Medicare Extra Help & Savings Programs in Utah (2026)
Medicare isn't free — but for lower-income Utah retirees, two federal programs can slash the cost. Extra Help (the Part D Low-Income Subsidy) can wipe out your drug-plan premium and deductible and drop copays to a few dollars, and it's now open to anyone with income up to 150% of the poverty level (CMS). The Medicare Savings Programs (QMB, SLMB, QI) help with Part A and Part B — QMB alone pays your $202.90 monthly Part B premium ($2,434.80 a year in 2026) plus deductibles and coinsurance. Best part: get a Savings Program and you're automatically enrolled in Extra Help too. Here are the 2026 income and resource limits and how a Utahn applies — with official sources.
Read →
Will Your Retirement Savings Last? The 4% Rule & Safe Withdrawal Rates in Utah (2026)
The real retirement question isn't how big your nest egg is — it's how long it will last. The 4% rule is a starting point: withdraw about 4% in year one, then adjust for inflation — roughly $20,000 a year on a $500,000 portfolio. But it's a dial, not a fact: about 1 in 3 of today's 65-year-olds will live past 90 (SSA), so plan for a 30-year retirement, and watch the three risks that break the math — living longer than average, a bad market early on, and the cost of long-term care (Utah assisted living runs about $4,685/month, CareScout). Here's how to build income you won't outlive — with official sources.
Read →
Working While Collecting Social Security: Utah's 2026 Earnings Test Guide
Claim Social Security early and keep working in Utah? The retirement earnings test can temporarily hold back part of your check. In 2026 you can earn up to $24,480 before full retirement age before Social Security withholds $1 for every $2 over the limit; in the year you reach FRA the limit jumps to $65,160 with only $1 withheld per $3 (SSA). Starting the month you reach FRA (67 for those born 1960+), there's no limit at all. Best part: withheld benefits aren't lost — your check is recalculated upward at FRA to credit them, and pensions, IRA withdrawals, and annuity income never count. Here's the 2026 math with a worked example and official SSA sources.
Read →
Working Past 65 in Utah: Medicare, Your Employer Plan & the Part B Penalty (2026)
Still working at 65? Whether you can delay Medicare comes down to one number — 20 employees. At an employer with 20 or more, the group plan pays first and you can usually wait. Under 20, Medicare pays first, and delaying can leave bills nobody covers. When the job ends you get an 8-month Special Enrollment Period; miss it and Part B costs 10% more for every full year late — for life, about $20.29/month per year against 2026's $202.90 premium (CMS). Add the COBRA trap and the HSA 6-month rule, and this is the decision Utah's late-career workers most often get wrong — with official sources.
Read →
Roth Conversions in Retirement: A Utah Guide for 2026
A Roth conversion moves pre-tax IRA or 401(k) money into a Roth IRA — you pay ordinary income tax now so it grows and comes out tax-free later. The payoff: Roth IRAs have no lifetime RMDs (IRS), while traditional accounts force taxable withdrawals at 73. In 2026 a married couple's 12% federal bracket tops out at $100,800 of taxable income (IRS), making low-income "gap years" prime conversion territory. But watch the side effects — a large conversion can raise Medicare IRMAA two years later (surcharges begin above $218,000 MAGI for joint filers) and make more of your Social Security taxable. Here's how it works, the 2026 numbers, and the traps — with official sources.
Read →
Medicare Part D in 2026: The $2,100 Out-of-Pocket Cap & the New Payment Plan — A Utah Guide
For the first time, Medicare Part D puts a hard ceiling on what you pay for covered drugs — $2,100 out of pocket in 2026, up from $2,000 in 2025 (CMS). The maximum deductible rises to $615, you pay 25% coinsurance until you hit the cap, and the old “donut hole” is gone. The free, voluntary Medicare Prescription Payment Plan can spread that spending into monthly payments. Here's how the redesigned benefit works and what Utah retirees should check before the Dec 7 deadline — with official sources.
Read →
The 2026 Social Security COLA & Medicare Part B: What Utah Retirees Will Actually Take Home
Social Security's 2026 cost-of-living adjustment is 2.8%, lifting the average retired-worker check about $56/month — from $2,015 to $2,071 (SSA). But the Medicare Part B premium jumps to $202.90 (up $17.90) and the deductible to $283 (CMS), so the average retiree's net raise is closer to $38/month. Here's the plain-English Utah math — budget the net, watch the tax line, and mind IRMAA — with official SSA and CMS sources.
Read →
VA Aid & Attendance in Utah: The Pension That Helps Veterans Pay for Care (2026)
If you or your late spouse served in wartime, a tax-free VA benefit can help pay for long-term care — and most families never claim it. In 2026, Aid & Attendance is worth up to $2,424/month for a Veteran, $2,874/month with a spouse, and $1,558/month for a surviving spouse (VA). With Utah assisted living near $4,685/month (CareScout 2024), it can cover a real slice of the bill. Here's who qualifies, the $163,699 net-worth limit, the 3-year look-back, and how it fits a plan.
Read →
Final Expense (Burial) Insurance in Utah: What It Covers, What It Costs & How It Works (2026)
A funeral with viewing and burial runs a national median of about $8,300 — roughly $9,995 with a vault, and about $6,280 with cremation (NFDA 2023). Final expense insurance is a small whole-life policy (usually $2,000–$25,000) built to pay that bill in cash. Here's how simplified- vs. guaranteed-issue coverage works, the two-year graded death benefit, and when a Utah family does — and doesn't — need one.
Read →
Hybrid Life + Long-Term Care Insurance: A Utah Guide to Asset-Based LTC (2026)
Tired of "use it or lose it"? A hybrid (asset-based) policy pairs a life-insurance death benefit with a long-term care benefit, so someone gets paid whether or not you need care. Americans bought $4.2 billion of new hybrid life/LTC premium across ~450,000 policies in 2024 (LIMRA), yet only 3–4% of adults over 50 own any LTC coverage. Here's how hybrids compare to traditional LTC, the tax rules (income-tax-free benefits under IRC §7702B and 1035 exchanges), and what Utah care actually costs — a private nursing-home room runs about $127,750/year (CareScout 2024).
Read →
Medicaid Estate Recovery in Utah: Can the State Take Your Home? (2026)
Medicaid pays for the care — then, after death, Utah's Office of Recovery Services can ask the estate for the money back. Federal law requires recovery of care paid at age 55 or older (Medicaid.gov), and Utah DHHS is explicit that a home exempt for eligibility is NOT exempt from estate recovery. Here's who's protected (surviving spouse, child under 21, blind or disabled child), how TEFRA liens work, and why it matters when Utah's median home is worth $489,400 (Census, ACS 2020–2024).
Read →
Required Minimum Distributions in 2026: A Utah Guide to Age 73, the 25% Penalty & QCDs
Tax-deferred savings don't stay deferred forever. RMDs start the year you turn 73 (75 if you were born in 1960 or later), and the excise tax on a missed one is 25% — 10% if corrected within two years (IRS). Here's how the math works (a $500,000 IRA owes about $18,868 at 73, using the IRS Uniform Lifetime Table), how it hits your Utah and federal taxes plus Medicare IRMAA, and how a qualified charitable distribution — up to $111,000 in 2026 — can satisfy an RMD without adding taxable income.
Read →
Is Social Security Taxable in Utah? The 2026 Credit, the Federal Rules & What Changed
Utah still taxes Social Security — but a state credit can erase that tax entirely. Starting with the 2026 tax year the credit begins phasing out above $90,000 of modified AGI for joint filers and $54,000 for single filers, dropping 2.5¢ per dollar (Utah Code 59-10-1042). Federally, up to 85% of benefits can be taxed above $34,000/$44,000 of combined income (SSA), and a new $6,000 senior deduction runs 2025–2028 (IRS). Here's how the pieces stack — with official sources.
Read →
Medicare Advantage vs. Medigap in Utah: 2026 Guide
Medicare Advantage or Medigap? Both fill Original Medicare's gaps, but in opposite ways. In 2026 an Advantage plan caps in-network out-of-pocket costs at up to $9,250 (CMS) for a low or $0 premium with a network, while Medigap Plan G leaves you just the $283 Part B deductible and works with any Medicare doctor nationwide (no drug coverage). Here's the side-by-side, plus Utah's 2025 birthday rule — with official sources.
Read →
How Annuities Work: A Utah Guide to Fixed, Indexed, Variable & Income Annuities (2026)
An annuity is a contract with an insurance company — not a bank deposit, not FDIC insured, and not an investment guarantee. Here's how the four deferred types work (a fixed indexed annuity can't credit less than 0%; a variable annuity can lose principal — SEC), what surrender charges really cost (typically 6–8 years, sometimes 10), Utah's best-interest rule for annuity sales (R590-230), and the questions the SEC says to ask before you sign.
Read →
Medicare IRMAA in 2026: A Utah Guide for Higher Earners
Most Utah retirees pay the standard $202.90 Medicare Part B premium in 2026 — but higher earners pay IRMAA on top, up to $689.90/month for Part B ($487 extra) plus a $91 Part D add-on, triggered by 2024 income (CMS/SSA). Here's how the 2026 brackets work, why a two-year-old tax return sets your premium, and how Utah households plan around the thresholds — with official sources.
Read →
Social Security Spousal Benefits: A Utah Guide for Married & Divorced Couples (2026)
A Social Security spousal benefit can be up to 50% of your husband's or wife's full benefit — but only about 32.5% if you claim at 62 (SSA). Here's how spousal and divorced-spouse benefits work in 2026, the deemed-filing rule that ended the old switch strategy, the 10-year rule for claiming on an ex, and how Utah couples coordinate two checks — with official SSA sources.
Read →
Do You Still Need Life Insurance After 60? A Utah Guide to Term, Whole & Final Expense (2026)
After 60, the real question isn't how much life insurance you can get — it's who still relies on your money. Here's when coverage still makes sense, how term, whole/permanent, and final-expense policies differ, and what a funeral really costs ($8,300 median with burial; 59% of adults own coverage but ~102M need more — NFDA & LIMRA). With official sources.
Read →
Aging in Place in Utah: What Home Care Really Costs — and What Medicare Actually Covers (2026)
Most Utahns want to age at home — but full-schedule home care runs about $6,864–$7,245/month in Utah (2024 CareScout), more than assisted living, and Medicare caps home health at 28 hours a week of part-time skilled care while paying nothing for custodial-only help. Here's what aging in place really costs, exactly where Medicare stops, and how St. George-area families plan — with official sources.
Read →
Social Security Survivor Benefits: What Happens to a Utah Household's Income When a Spouse Dies (2026)
When a spouse dies, the household keeps only the larger Social Security check — the smaller one stops. Survivor benefits pay 71.5%–100% of the deceased's benefit depending on claiming age, and the average aged widow(er) receives $1,919/month in 2026 vs. $3,208 for a couple (SSA). Here's how the rules work, the switch strategy, and how Utah families fill the gap — with official sources.
Read →
Does Medicare Pay for Long-Term Care? The 100-Day Rule Every Utah Retiree Should Know (2026)
Medicare covers at most 100 days of skilled nursing care per benefit period — days 1–20 at $0, days 21–100 at $217/day in 2026 (CMS), then nothing. And it never pays for ongoing custodial care, which is most long-term care. Here's exactly where coverage ends and how Utah families plan for what comes after, with official sources.
Read →
Will Medicaid Pay for Long-Term Care in Utah? 2026 Limits, Spousal Protections & the 5-Year Look-Back
Utah Medicaid can pay for nursing-home care, but the 2026 limits are strict: about $2,982/month income and $2,000 in assets for a single applicant, with a 60-month look-back on gifts. Federal rules let a healthy spouse keep $32,532–$162,660 — barely more than one year in a Utah private nursing-home room. Here's how the rules work and why planning early matters, with official sources.
Read →
How Long-Term Care Insurance Works in Utah: Traditional vs. Hybrid Policies (2026)
Long-term care insurance pays a benefit once you need help with 2 of 6 activities of daily living (ACL) — but traditional and hybrid policies work very differently. Here's how each pays out, why hybrid life/LTC coverage is growing, what care costs in Utah (about $4,685/mo for assisted living, 2024 CareScout), and why Medicare won't fill the gap — with sources you can check.
Read →
How to Turn Retirement Savings Into Lifetime Income: A Utah Guide (2026)
A 65-year-old Utahn today lives to about 84–87 on average, and more than 1 in 3 will pass 90 (SSA). Here's how to turn savings into income that lasts as long as you do — the two-bucket paycheck, the 4% rule's limits, Social Security timing (up to $5,181/mo at 70 in 2026), and where annuities fit, with sources you can check.
Read →
Social Security: Claim at 62, 67, or 70? A Utah Guide (2026)
When should Utah retirees claim Social Security? Claiming at 62 cuts your benefit about 30% for life, while waiting until 70 adds about 24%. See the 2026 SSA numbers, a clear $2,000-benefit example, the earnings-limit rules, and how couples coordinate — with sources you can check.
Read →
The Real Cost of Long-Term Care in Utah (2024 Data) — and How to Plan for It
About 70% of people turning 65 will need long-term care, and Medicare won't pay for most of it. Here's what assisted living, home care, and nursing care actually cost in Utah (2024 CareScout data), how families pay for it, and why a plan matters — with sources you can check.
Read →